


Advertisement|Remove ads.
Apple 2027 Growth Outlook Faces Scrutiny — Analysts See iPhone Upside, Flag Services Slowdown And Margin Risks

- TD Cowen said its calendar 2027 EPS estimate of $9.75 remains achievable, citing improving 2-nanometer chip supply and roughly 12% iPhone revenue growth.
- Apple guided December-quarter gross margin to 45% to 46%, down from 47.9%, on higher memory and Siri AI costs.
- Barclays said Services growth slipped below 10%, while UBS flagged AI-driven search disruption as a risk.
Advertisement|Remove ads.
Apple (AAPL) drew mixed assessments from analysts on Tuesday following its fiscal fourth-quarter earnings, with several firms highlighting resilient iPhone demand while raising concerns about slowing Services growth and mounting pressure on profitability.
The company reported quarterly revenue of $114.5 billion on Monday, up 12% year over year, while iPhone revenue jumped 17% to $57.6 billion. However, its December-quarter outlook exposed a divergence between stronger product demand and weaker expectations for margins and Services.
As of this writing, AAPL stock was down nearly 3% and was among the top-trending tickers on Stocktwits.
Advertisement|Remove ads.
Analysts See iPhone Growth Supporting 2027 Outlook
According to the note cited by TheFly, TD Cowen said its calendar 2027 earnings per share estimate of $9.75 for Apple remains achievable, supported by improving 2-nanometer chip supply, roughly 12% iPhone revenue growth, and projected free cash flow of $140 billion to $150 billion.
Morgan Stanley said Apple's December-quarter revenue outlook exceeded expectations despite supply constraints, reinforcing its view of resilient product demand and pricing power.
However, the firm modestly reduced its fiscal 2027 earnings estimates as weaker Services growth and margins offset stronger revenue and cash flow, per TheFly.
Advertisement|Remove ads.
Argus highlighted strong iPhone performance and easing supply constraints, while Goldman Sachs remained optimistic about the iPhone refresh cycle despite softer iPad sales and weaker gross margin guidance.
Services Slowdown, Memory Costs Raise Questions
JPMorgan said the central investor debate would increasingly focus on the changing growth trajectories of hardware and Services. While iPhone revenue met expectations despite higher prices, the firm warned that slowing Services growth and headwinds from mobile gaming could challenge longer-term expectations.
UBS similarly flagged potential AI-driven search disruption, rising Siri costs and below-consensus margin guidance as risks to earnings forecasts. Barclays pointed to Services growth slipping below 10%, with further deceleration expected.
Advertisement|Remove ads.
Firm | Rating | Previous Target | New Target |
Argus | Buy | $375 | $400 |
Goldman Sachs | Buy | $390 | $380 |
TD Cowen | Buy | $400 | $390 |
Morgan Stanley | Overweight | $355 | $350 |
UBS | Neutral | $296 | $340 |
Barclays | Underweight | $245 | $261 |
Apple expects December-quarter revenue growth of 7% to 10%, but forecasts Services growth of just 8% to 9%. Gross margin is projected at 45% to 46%, down from 47.9% in the September quarter, reflecting higher memory costs and expenses associated with Siri AI.
Retail Investors’ Sentiment Around AAPL Stock
On Stocktwits, retail investors’ sentiment around Apple stock remained in the ‘bearish’ territory.
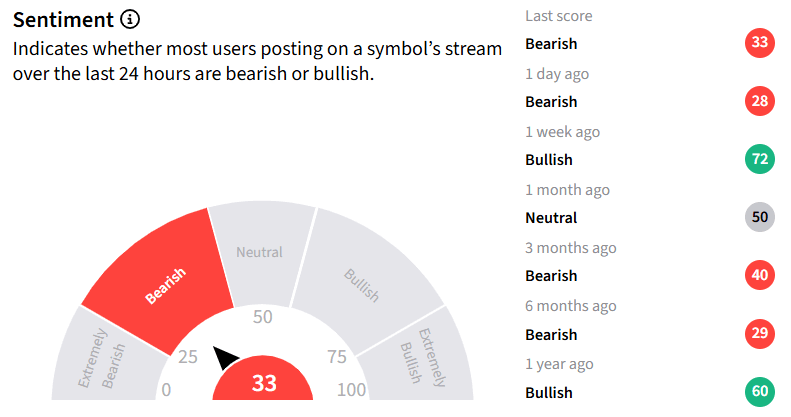
A bullish Stocktwits user posted that Apple's loyal customers are willing to pay premium prices, giving it stronger pricing power and a competitive edge as advanced AI hardware becomes scarcer.
Advertisement|Remove ads.
So far in 2026, AAPL stock has rallied over 21%. By comparison, the Vanguard Morningstar Growth ETF (VUG) and the Fidelity MSCI Information Technology Index ETF (FTEC), which hold the stock, have risen around 5% and 22%, respectively, over the same period.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Advertisement|Remove ads.
Comments posted here will also appear on symbol pages.

Latest News

 Anan Ashraf·7m ago
 Harshita Tyagi·42m ago

 Shashank Nayar·42m ago

 Arnab Paul·53m ago
 Heera Hari·59m ago
 Anushka Basu·1h ago