


Advertisement|Remove ads.
DPZ Stock Risks Ending Two-Week Rally: Domino’s CEO Flags ‘Items Per Order’ Pressure Amid Slowing Q3 Growth
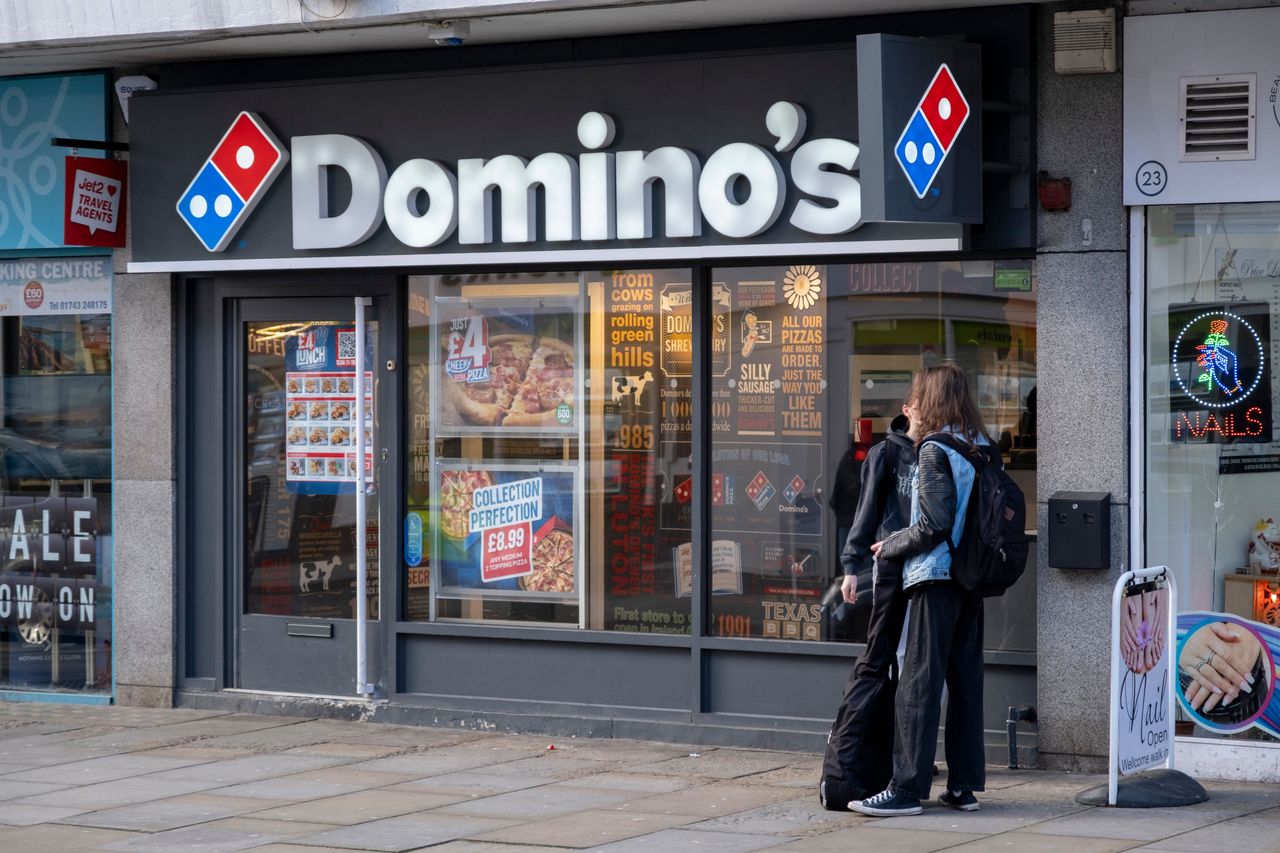


- Domino’s Pizza Q3 U.S. same-store sales growth slowed to 0.3%.
- CEO Joe Jordan said budget-conscious customers are ordering fewer items.
- The company expects consumer pressures to persist through 2026.
Domino’s Pizza Inc. (DPZ) stock is heading for a weekly loss after its third-quarter (Q3) results beat Wall Street estimates but showed customers cutting back on orders to protect their budgets. New CEO Joe Jordan warned that consumer pressure would persist through year-end and guided for U.S. same-store sales growth at the low end of its forecast range.
Domino’s Pizza stock edged up 0.6% overnight ahead of Wednesday, after dropping more than 4% in the regular session.
Domino’s Q3 Earnings Beat Mask Weakening Same-Store Sales Growth
Tuesday’s stock decline ends a two-week winning streak and highlights the central tension in the Domino’s story. Customers are still ordering, but they are buying less each time. On the surface, the quarter was solid. Domino’s reported net income of $152.2 million, or $4.60 per share, up from $139.3 million, or $4.08, a year earlier. Revenue rose to $1.19 billion from $1.15 billion. Both topped the analysts’ consensus estimates of $1.17 billion and $4.38, respectively, according to Fiscal.ai data.
Advertisement|Remove ads.
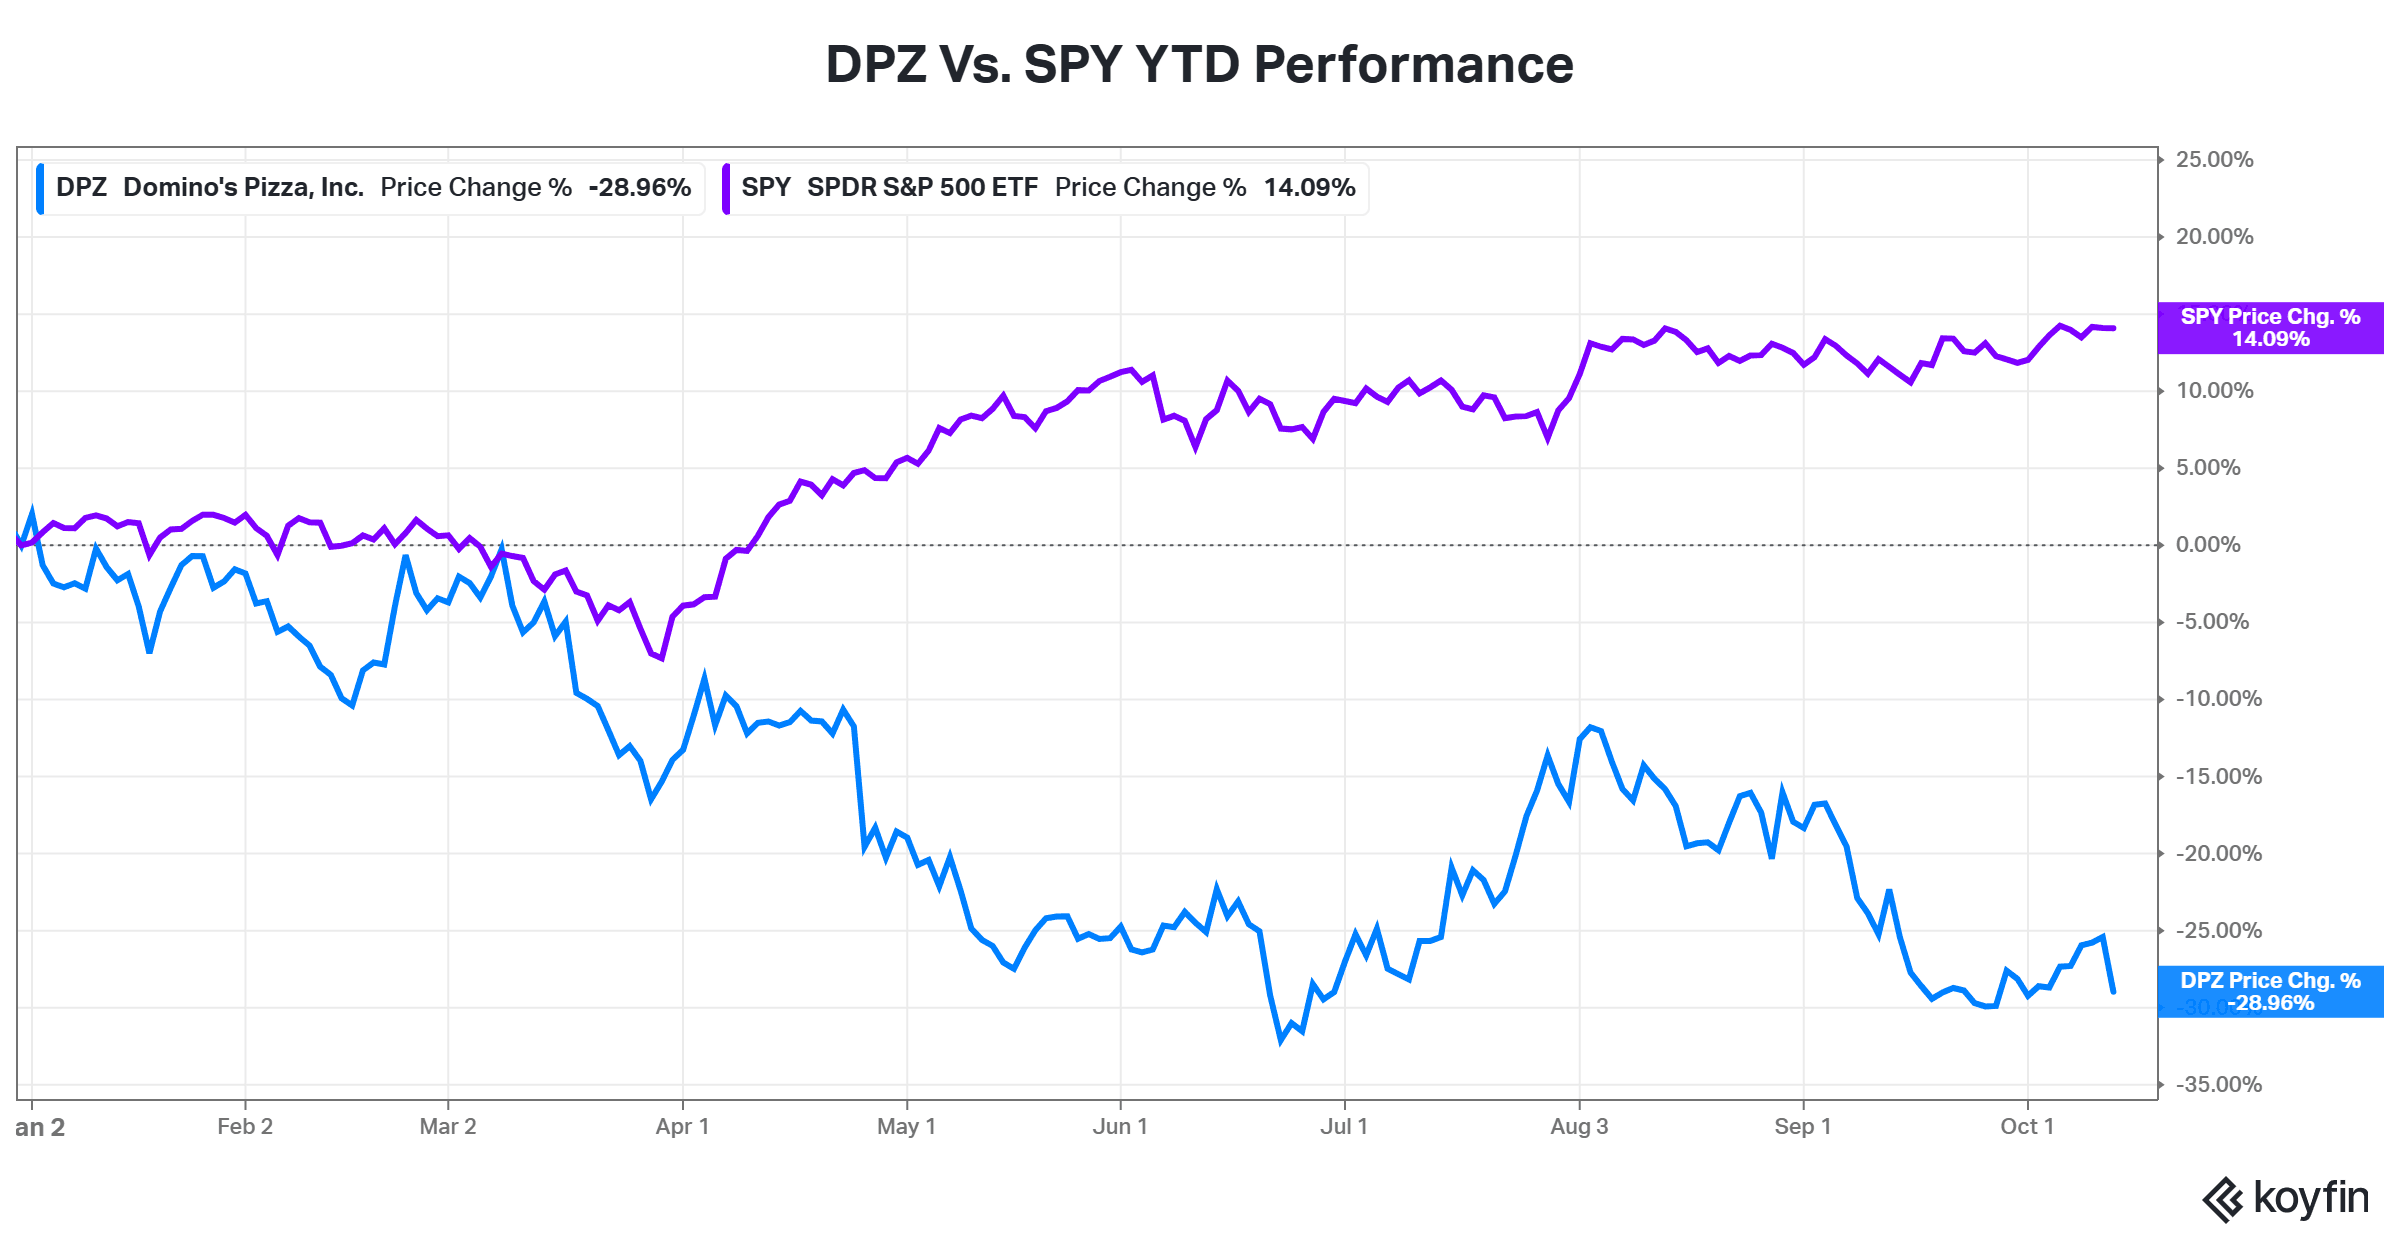
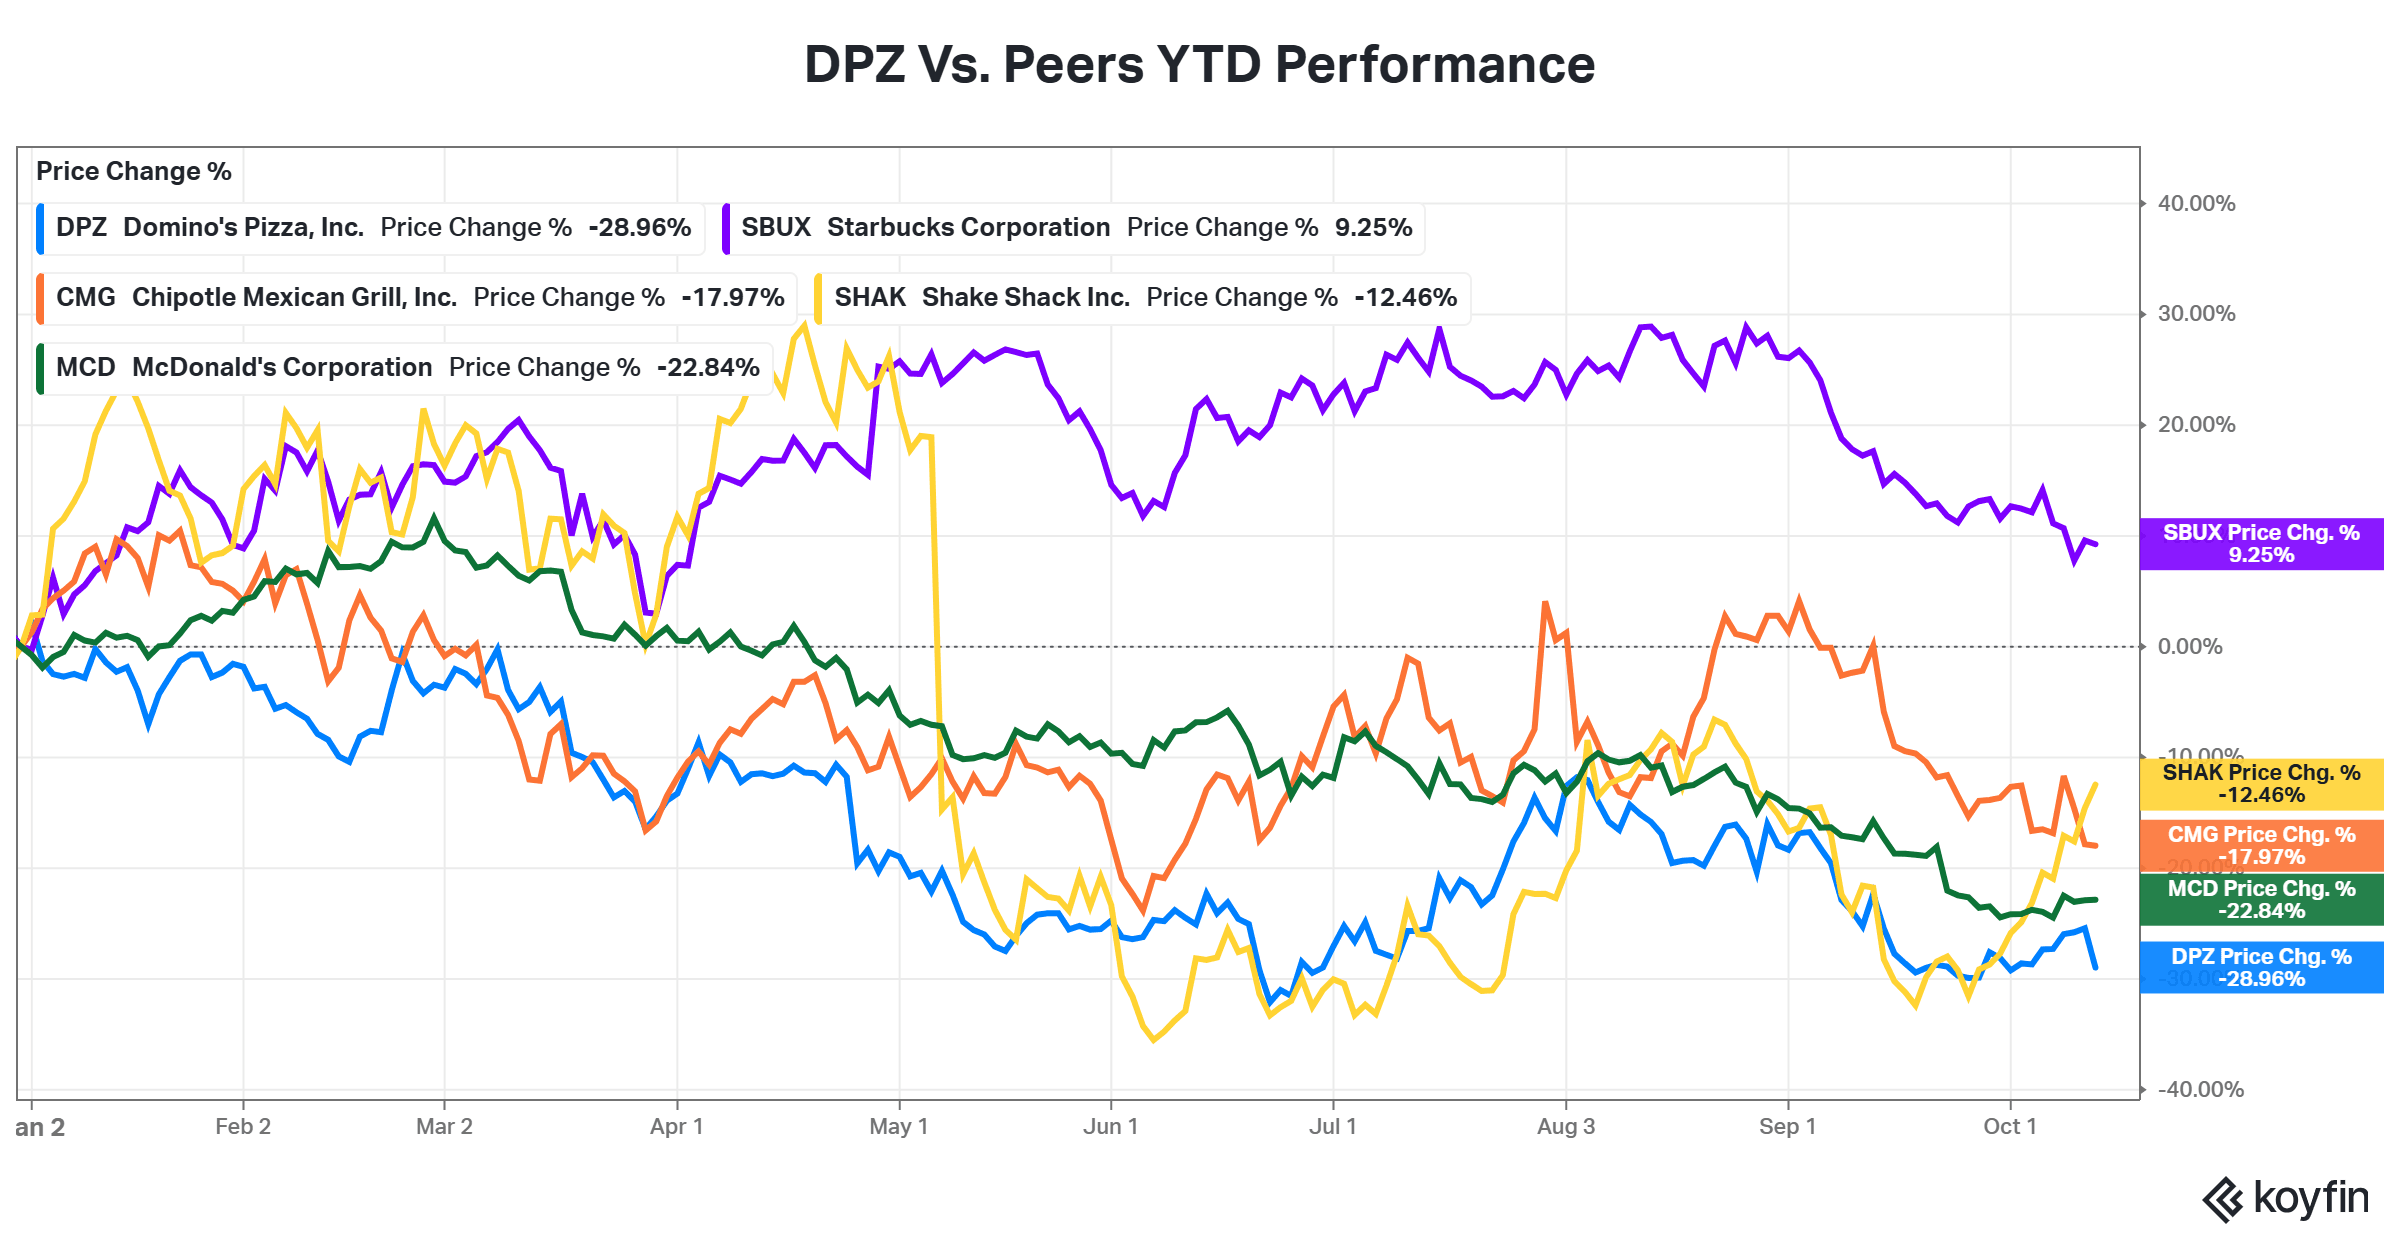
The growth quality is the concern. U.S. same-store sales rose just 0.3%, a sharp deceleration from 5.2% in the year-ago quarter. International same-store sales rose 0.2%. Global retail sales growth slowed to 3.2% from 6.3%, reaching $4.84 billion. Store count grew 4.4%, so expansion, not existing locations, is doing the heavy lifting. With the stock down about 29% year-to-date, investors are weighing whether the pizza giant’s value strategy can protect profits when consumers are stretched.
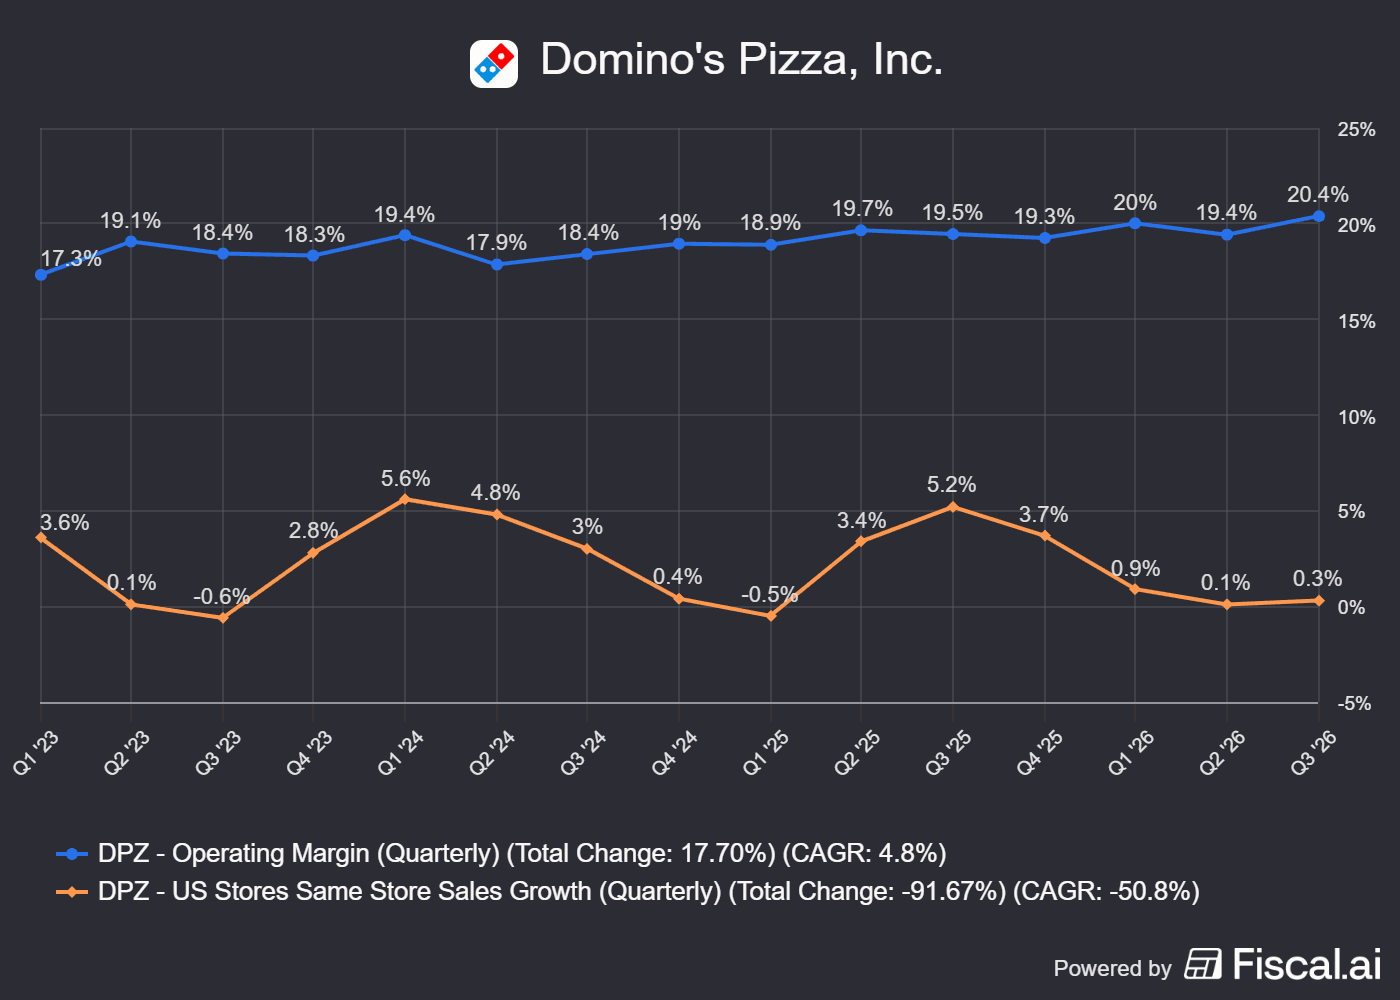
The quarterly trend shows the slide. Domino’s U.S. same-store sales growth has swung sharply over the past three years while its operating margin has stayed steady. Comparable sales peaked at 5.6% in Q1 2024 and again at 5.2% in Q3 2025, but have since faded to 3.7% in Q4 2025, 0.9% in Q1 2026, 0.1% in Q2 and just 0.3% in Q3 2026, which is roughly flat.
Operating margin has stayed between roughly 17% and 20%, rising from 17.3% in Q1 2023 to a high of 20.4% in Q3 2026. This suggests Domino’s franchise-based business is helping protect profits. However, same-store sales growth only edged up to 0.3% in Q3.
Advertisement|Remove ads.
Domino’s Sees Smaller Orders As Consumer Pressures Persist
It was Jordan’s first earnings call as CEO. He succeeded Russell Weiner this month after serving as chief operating officer, and his message was blunt about where the strain shows up.
“So the brand is still relevant, even when the pressure is on their pocketbooks,” Jordan said. “But in Q3, we believe that manifested mostly in items per order. So we had pressure on items per order, so customers were still coming to us, but managing their ticket by managing items per order.”
Advertisement|Remove ads.
In other words, traffic is not the problem. Basket size is. Diners are skipping the extra side, dessert, or second pizza, even as they keep choosing Domino’s for dinner. Jordan offered little near-term relief. “Looking ahead to the remainder of 2026, we expect the macro environment to remain an overhang on the consumer through the balance of the year.”
CFO Sandeep Reddy put numbers on that caution. Domino’s still expects U.S. comparable sales to rise at a low-single-digit rate, but Reddy said that after three quarters, the company believes it will land “towards the low end of that range.” That assumes the “challenging macroeconomic and competitive environment” seen so far persists.
International is weaker. Domino’s now expects international same-store sales growth to be roughly flat for the year, citing continued pressure at DPE, its Domino’s Pizza Enterprises franchise partner.
Advertisement|Remove ads.
Wall Street Reacts To Domino’s Q3 Performance
TD Cowen kept its ‘Hold’ rating and $320 price target. The analyst noted that management alluded to continued ticket pressure in Q4 amid “no quick fix” in a challenged pizza category. The firm cut its Q4 U.S. comp estimate to 1% from 1.5%. It also does not expect “sweeping changes” when Jordan lays out his strategic plan with Q4 results.
Morningstar analyst Ari Felhandler remained positive about Domino’s despite trimming his forecasts. He believes discounts are attracting cost-conscious customers, while rising orders show that the company’s affordable prices and new menu items are appealing amid economic uncertainty and heavy competition.
Domino’s marketing muscle and franchisee model may give it more room to price aggressively than rivals such as Papa John’s International (PZZA) and Yum! Brands (YUM), parent of Pizza Hut. Morningstar expects the chain to use targeted promotions to increase items per order, which could boost restaurant-level profit.
Advertisement|Remove ads.
Still, the weaker outlook is changing the growth math. Morningstar cut its 2026 U.S. net store opening forecast to 125 to 150, in line with management’s revised target and down from its prior estimate of 167. It sees roughly 75 openings in 2027 as competition and soft domestic demand weigh on expansion.
DPZ Stock: Retail View
On Stocktwits, retail sentiment around the stock improved to ‘bullish’ from ‘neutral’ the previous day. Message volume jumped 800% over the past week, with watchers up 0.2%.
DPZ stock has cratered 30% in the last twelve months.
Advertisement|Remove ads.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Comments posted here will also appear on symbol pages.

Latest News
 Preeti Ayyathurai·16m ago
 Deepti Sri·20m ago

 Yuvraj Malik·25m ago

 Aashika Suresh·31m ago
 Deepti Sri·43m ago
 Shivani Kumaresan·59m ago