


Advertisement|Remove ads.
NOW Stock On Track To Post Worst Single-Day Performance In Over 14 Years — Analysts See AI Upside Despite Slowing Growth

- ServiceNow’s Q3 revenue rose 20.5% to $4.11 billion, beating estimates, but adjusted EPS of $1 missed expectations.
- Cantor Fitzgerald viewed the sell-off in ServiceNow stock as an AI-driven buying opportunity.
- RBC Capital flagged a gap between management's optimistic AI commentary and its financial outlook.
Advertisement|Remove ads.
ServiceNow (NOW) shares plunged over 25% on Thursday, putting the stock on track for its worst single-day performance in over 14 years, as investors reacted to the company's softer-than-expected outlook for fourth-quarter contracted revenue growth.
The enterprise software firm’s fiscal third-quarter (Q3) revenue increased 20.5% year over year to $4.11 billion, ahead of the $4.09 billion consensus estimate tracked by FiscalAI.
However, adjusted earnings per share (EPS) of $1 missed expectations of $1.02. The company raised its full-year subscription revenue outlook and increased its 2026 AI annual contract value target to $1.7 billion.
Advertisement|Remove ads.
At the time of this writing, NOW stock was trading over 25% lower and was among the top-trending tickers on Stocktwits.
Analysts See AI Upside Despite Sell-Off
ServiceNow expects current remaining performance obligations (cRPO) growth of 18.5% in the fourth quarter, below analysts' expectations of 19.8% and slowing from 20.5% in the third quarter.
According to TheFly, Cantor Fitzgerald viewed the post-earnings selloff as an AI-driven buying opportunity, highlighting strong seat growth, AI demand, federal momentum and security consolidation. The firm expects continued AI adoption, consumption growth and potential margin expansion.
Advertisement|Remove ads.
JPMorgan maintained that ServiceNow's momentum continues despite the "noisy" quarterly report, pointing to visibility into longer-term growth drivers and potential acceleration in AI monetization.
Wells Fargo remained constructive on the company's AI opportunity, particularly its position in enterprise AI orchestration, while Barclays noted that ServiceNow's broader growth story remained intact despite near-term pressures and the sharp post-earnings selloff.
Analysts Flag Growth And AI Risks
RBC Capital said investors were struggling to reconcile management's optimistic AI commentary with quarterly performance and fourth-quarter guidance, according to the Note cited by TheFly.
Advertisement|Remove ads.
Citi, meanwhile, said ServiceNow's AI acceleration may require more patience, while UBS noted that Wall Street's 2027 growth estimates appeared elevated. KeyBanc highlighted that elevated investor expectations ahead of earnings had called for stronger and cleaner results.
TD Cowen noted that subscription revenue recognition headwinds from new AI service delivery contributed to a smaller-than-expected revenue beat. BTIG also highlighted results falling short of investor expectations, particularly given crowded positioning ahead of earnings.
| Brokerage | Rating | New Target | Previous Target | Change From Last Close |
| Cantor Fitzgerald | Overweight | $201 | Unchanged | +33.9% |
| Baird | Outperform | $185 | $125 | +23.2% |
| Wells Fargo | Overweight | $175 | $190 | +16.6% |
| Mizuho | Outperform | $165 | $170 | +9.9% |
| Morgan Stanley | Overweight | $160 | $180 | +6.6% |
| JPMorgan | Overweight | $160 | $150 | +6.6% |
| KeyBanc | Underweight | $110 | $85 | -26.7% |
| UBS | Neutral | $140 | $150 | -6.7% |
What Retail Thinks About NOW Stock
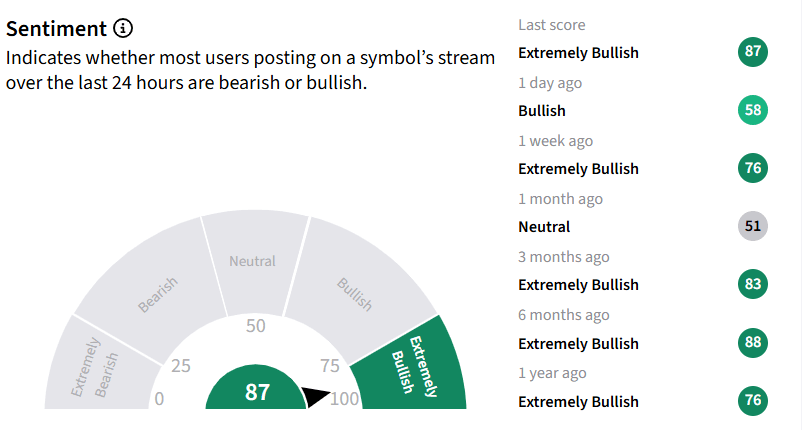
Despite the sell-off, retail investors’ sentiment around NOW stock improved to ‘extremely bullish’ from ‘bullish’ earlier amid extremely high user message volume.
Advertisement|Remove ads.
After Thursday’s decline, NOW stock has erased all of this year's gains and is now down 24% on a YTD basis. By comparison, the iShares Expanded Tech-Software Sector ETF (IGV), which holds the stock, has risen over 4% over the same period.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Advertisement|Remove ads.
Comments posted here will also appear on symbol pages.
Latest News
 Shashank Nayar·10m ago
 Anan Ashraf·45m ago
 Heera Hari·1h ago
 Arnab Paul·1h ago
 Harshita Tyagi·1h ago
 Harshita Tyagi·2h ago