


Advertisement|Remove ads.
ENPH Stock Drops After-Hours As Interest Rates And Tax Credit Expiry Hit US Solar Demand

- Q3 revenue reached $293.3 million, up slightly from the prior quarter but well short of analyst estimates near $305 million.
- Looking ahead, Enphase guided fourth-quarter revenue to $225–$255 million, including about $51.2 million of safe-harbor sales and battery shipments of 100–120 megawatt-hours.
- Despite soft near-term demand, the company pegged a solid-state transformer for AI data centers as a long-term demand driver.
Advertisement|Remove ads.
Shares of Enphase Energy (ENPH) tumbled about 16% in after-hours trading on Tuesday after the solar technology company reported third-quarter results that missed Wall Street expectations and issued a cautious fourth-quarter forecast.
ENPH Weighed Down By Soft Demand
Revenue reached $293.3 million, up slightly from the prior quarter but well short of analyst estimates near $305 million. Adjusted earnings came in at $0.41 per share, missing consensus of roughly $0.50, according to data from Fiscal AI. Global sell-through, or the proportion of total inventory shipped to retailers that is purchased by end customers, rose only about 1% sequentially, far below the company’s own expectation of roughly 10% growth, pushing results toward the low end of the company’s own guidance of $290 million to $320 million.
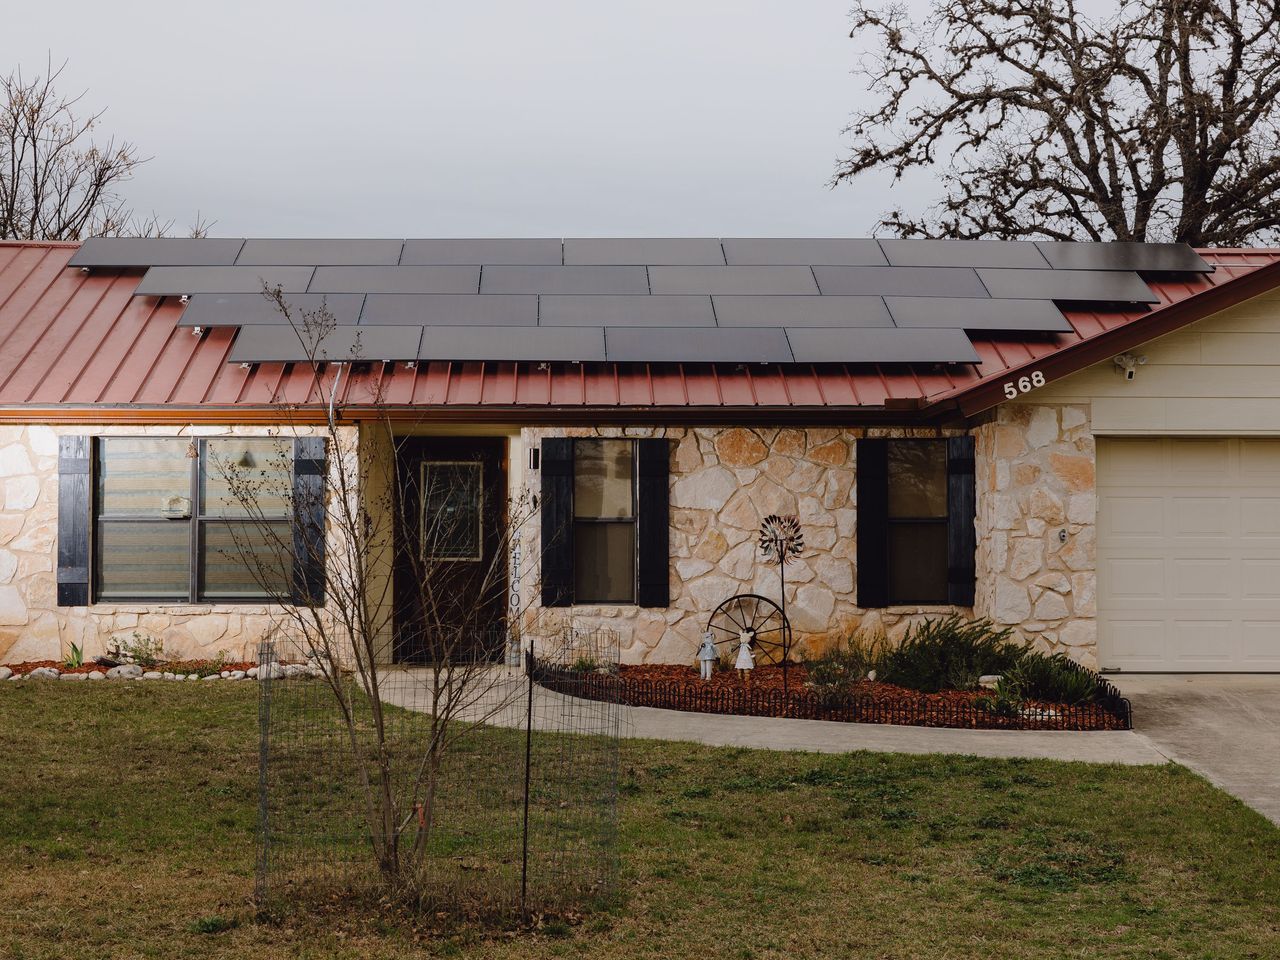
CEO Badri Kothandaraman noted that U.S. sell-through increased a modest 5% from the second quarter but fell 35% year-over-year, in line with broader residential solar permit declines. He attributed the pressure to elevated interest rates and the expiration of the tax credit that allowed homeowners to deduct 30% of the cost of installing qualifying renewable energy systems. European revenue dropped about 11% sequentially amid summer seasonality and softer conditions, particularly in France, where battery and microinverter activations declined.
Advertisement|Remove ads.
Enphase’s Outlook
Looking ahead, Enphase guided fourth-quarter revenue to $225–$255 million, including about $51.2 million of safe-harbor sales and battery shipments of 100–120 megawatt-hours. Management expects global sell-through to decline roughly 10% sequentially and plans to ship about $20 million below sell-through to further trim channel inventory ahead of a seasonally slow first quarter.
“With Q1 2027 expected to be seasonally slow, we anticipate distributors will remain cautious about building inventory heading into the new year, ” Kothandaraman said.
Despite soft near-term demand, CEO Badri Kothandaraman pointed to five longer-term growth drivers: next-generation home batteries targeting roughly 50% higher shipments in 2027, a prepaid-lease program called Propel, commercial solar and storage systems, bidirectional EV chargers, and a solid-state transformer for AI data centers.
Advertisement|Remove ads.
He noted a pipeline of more than 50 potential customers for the transformer—including a major cloud provider and a leading AI computing company—with pilot projects expected in 2027 and commercial sales in 2028. Enphase currently holds an estimated 15–20% share of the U.S. residential battery market and sees a sizable opportunity to sell batteries to homes that already use its solar equipment.
How Did ENPH Retail Traders React?
On Stocktwits, retail sentiment around ENPH stock jumped from 'bearish' to 'extremely bullish' territory over the past 24 hours, while message volume rose from 'low' to 'extremely high' levels.
A Stocktwits user expressed optimism about the company’s plans to tap into the AI data center energy demand, but noted that it is “distant.”
Advertisement|Remove ads.
Another user noted that the earnings report is “bad” but opined that the market will eventually look over to the company’s potential with AI data center energy demand.
Advertisement|Remove ads.
A third user noted that the stock is back to 2019 levels, when it traded mostly in the mid-to-high $ 20s.
ENPH stock has dropped 7% year-to-date.
Advertisement|Remove ads.
Read More: TSLA Stock Rises As Cybercabs Overtake Model Ys In Authorized Texas Robotaxi Fleet
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Comments posted here will also appear on symbol pages.
Latest News
 Shashank Nayar·27m ago
 Shashank Nayar·36m ago
 Anan Ashraf·40m ago
 Shashank Nayar·2h ago
 Anan Ashraf·2h ago
 Anan Ashraf·3h ago