


Advertisement|Remove ads.
Fed Rate Decision Today: Here’s What Goldman Strategist Has To Say About Interest Rates

- According to Goldman Sachs strategist Vickie Chang, the firm's economists believe there may be only one more interest rate increase.
- The S&P 500 gained 34% in the year following the Fed's single rate hike in 1997 and around 9% in the 12 months after its 2015 rate hike.
- The CME FedWatch Tool data showed traders assigned a 92.8% probability of unchanged rates at the October meeting.
Advertisement|Remove ads.
As the Federal Reserve gears up to announce its policy decision, Goldman Sachs macro strategist Vickie Chang reportedly noted that economists at the firm believe there may be only one more interest rate increase, compared with markets’ expectation of three additional hikes.
According to a CNBC report, Chang said that either outcome would make the current cycle one of the smallest rate-hiking cycles since 1983.
The strategist compared the current outlook with three relatively short tightening cycles: 1997, 2015 and the period between June 1999 and May 2000.
Advertisement|Remove ads.
What Previous Fed Rate-Hike Cycles Show
If the Fed delivers three more quarter-percentage-point increases, cumulative tightening would reach approximately 100 basis points or 1% in the current cycle. Just one additional hike would bring the total to 50 basis points.
Chang identified the single-hike cycles of 1997 and 2015 as the closest comparisons to Goldman Sachs' current expectations. “Equities fell initially in both cycles but troughed quickly in 1997 and rallied strongly,” she stated in a note cited by the publication.
S&P 500’s Historical Gains Following Fed Rate Hikes
According to the report, the S&P 500 gained 34% in the year following the 1997 increase and approximately 9% over the 12 months after the 2015 hike. The index also advanced around 9% during the June 1999-May 2000 period, when the Fed raised rates by 175 basis points.
Advertisement|Remove ads.
Chang also identified similarities between today's investment boom and the 1999 economic environment, while noting that the macroeconomic imbalances present then are generally less visible now.
“The market expects a more extended series of hikes than in 1997 and 2015, although short of the 175bps delivered in 1999,” she said.
Fed Expected To Hold Rates Despite Elevated Inflation
The analysis comes ahead of Wednesday's Federal Open Market Committee (FOMC) decision, with investors widely expecting the central bank to leave its benchmark interest rate unchanged at 3.75% to 4.00%.
Advertisement|Remove ads.
The CME FedWatch Tool data showed traders assigned a 92.8% probability of rates remaining unchanged at the October meeting, compared with a 7.2% probability of a quarter-point hike. For the December 9 meeting, market pricing indicated an 87.6% probability that rates would be higher than their current level.
The Fed last raised rates by 25 basis points in September, its first increase in more than three years. The policy outcome is eyed closely as U.S. inflation remains above the Fed's 2% target.
The Consumer Price Index rose 3.7% year over year in September, accelerating from 3.4% in August. Core inflation, which excludes food and energy, increased 2.6% annually, according to the Bureau of Labor Statistics.
Advertisement|Remove ads.
What Investors Are Watching
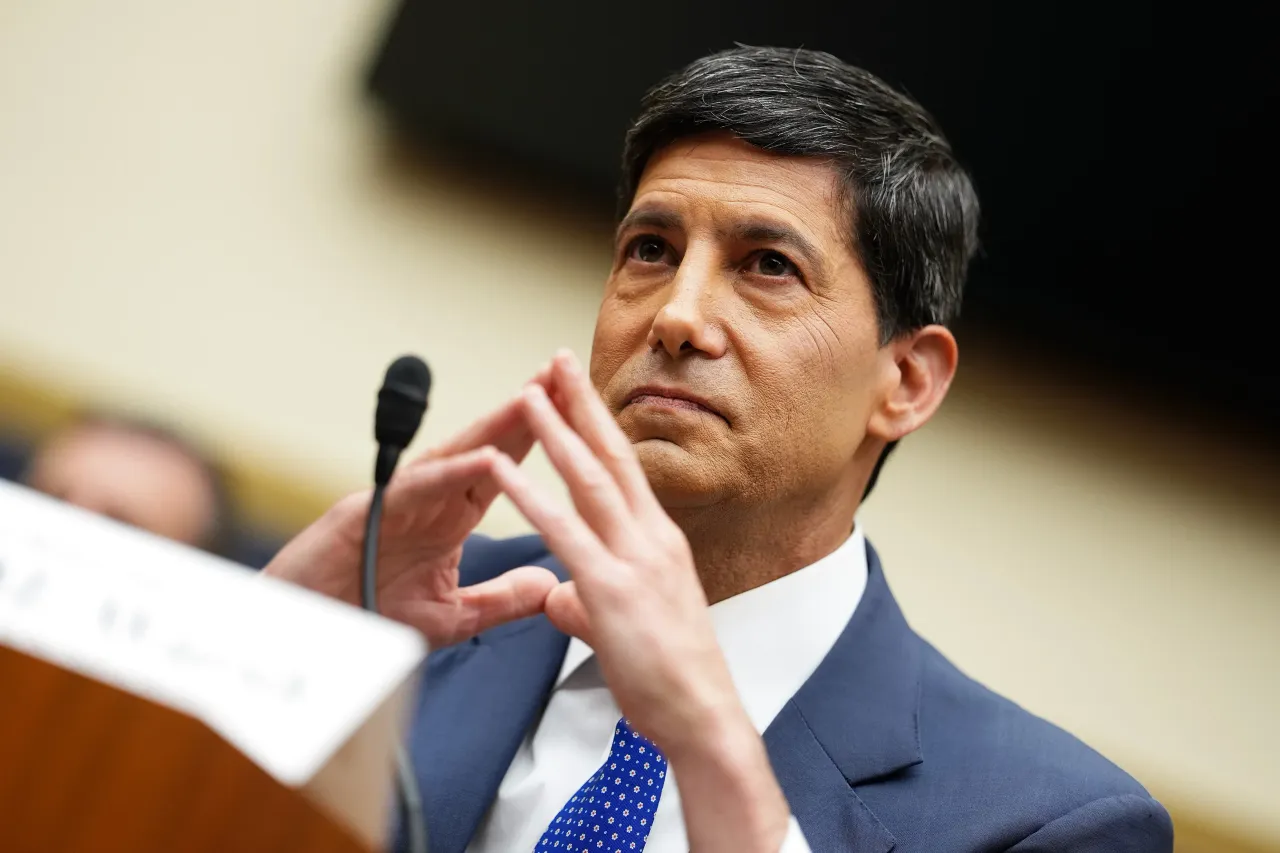
Investors will be watching Wednesday's policy decision and Fed Chair Kevin Warsh's comments for indications of the central bank's next move.
Ahead of the FOMC outcome, market indices edged higher on Wednesday. The S&P 500 rose 0.26%, while the Dow Jones Industrial Average gained 0.3%. The Nasdaq Composite edged up 0.1%, while the tech-heavy Nasdaq-100 advanced 0.26% at the time of this writing.
On Stocktwits, retail sentiment toward the SPDR S&P 500 ETF (SPY) improved to ‘neutral’ and toward the Invesco QQQ Trust (QQQ) to ‘bearish’, while sentiment toward the SPDR Dow Jones Industrial Average ETF Trust (DIA) remained ‘bearish’.
Advertisement|Remove ads.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Comments posted here will also appear on symbol pages.
Latest News
 Shashank Nayar·32m ago
 Anushka Basu·45m ago
 Arnab Paul·49m ago
 Shashank Nayar·59m ago
 Harshita Tyagi·59m ago
 Heera Hari·1h ago