


Advertisement|Remove ads.
LCRX Stock: Morgan Stanley Raises Price Target, Sees 50% Shipment Growth In 2026

- Morgan Stanley raised its Lam Research price target and maintained an ‘Overweight’ rating.
- The firm expects a “solid” December-quarter beat from Lam Research.
- Lam’s system-shipment growth is forecast at 47% in 2027.
Advertisement|Remove ads.
Lam Research (LRCX) is heading into its next earnings report with Wall Street increasingly bullish on the semiconductor-equipment cycle.
On Monday, Morgan Stanley raised its price target to $385 from $367 while maintaining an ‘Overweight’ rating, citing increased confidence in the durability of the company's leading logic share gains.
According to TheFly, analyst Shane Brett said the firm is "more confident than ever" that those gains can persist and expects Lam to deliver a "solid" December-quarter beat. The firm also raised its system-shipment growth forecasts to 50% for calendar 2026 and 47% for 2027.
Advertisement|Remove ads.
At the time of this writing, LCRX stock was trading 1% down in Monday’s premarket session.
Lam Heads Into Earnings With Revenue Momentum
Lam entered the current quarter after reporting record June-quarter revenue of $6.72 billion, up 15% sequentially. Systems revenue rose to $4.25 billion from $3.73 billion in the March quarter.
For the September quarter, the company guided revenue to $8.10 billion. At the midpoint, that would represent roughly 20% sequential growth.
Advertisement|Remove ads.
The company also guided non-GAAP gross margin to 52% and operating margin to 39.5%.
Foundry Spending Supports Systems Growth
Lam’s fiscal 2026 revenue rose 26% to $23.23 billion, while systems revenue increased nearly 30% to $14.89 billion. The company said higher spending from foundry-equipment customers drove the increase in systems revenue.
Foundry accounted for 44% of June-quarter systems revenue, while logic and other customers contributed 10%. Dynamic random-access memory (DRAM) and non-volatile memory each represented 23%.
Advertisement|Remove ads.
Lam is scheduled to report its September-quarter results on Oct. 21, providing the next read on demand and the setup heading into the December quarter that Morgan Stanley expects to be “strong”
What Retail Thinks About LRCX Stock
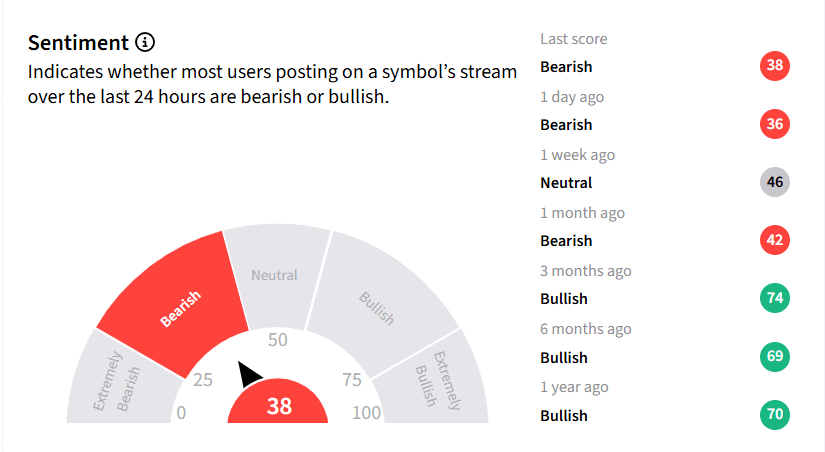
On Stocktwits, retail sentiment around LRCX stock continues to remain ‘bearish’.
So far this year, LRCX stock has rallied nearly 88%. In comparison, the VanEck Semiconductor ETF (SMH), and the State Street Technology Select Sector SPDR ETF (XLK), which hold the stock, have risen around 69% and 38%, respectively, over the same period.
Advertisement|Remove ads.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Comments posted here will also appear on symbol pages.

Latest News

 Arnab Paul·7m ago

 Anushka Basu·25m ago

 Harshita Tyagi·40m ago
 Prabhjote Gill·42m ago
 Harshita Tyagi·1h ago

 Heera Hari·1h ago