


Advertisement|Remove ads.
Palo Alto’s AI Ambitions Come With A Catch — Why Morningstar Calls PANW’s $4.5B Deal 'Risky'


- Palo Alto’s first-quarter sales rose 39% year-over-year to $3.44 billion, beating the $3.31 billion consensus estimate.
- Morningstar assigned Palo Alto a “Very High” Uncertainty Rating, citing rapid technological change and disruption from smaller rivals.
- Jefferies raised its price target to $450 from $400, saying “AI tailwinds starting to emerge.”
Advertisement|Remove ads.
Palo Alto Networks' (PANW) proposed $4.5 billion acquisition of Applied Compute could put the cybersecurity company in competition with frontier artificial intelligence (AI) research labs, according to Morningstar, which described the deal as “risky.”
Morningstar called the acquisition “distinctly non-cybersecurity” in nature, but said it could let Palo Alto train AI models tailored to cybersecurity while reducing its dependence on frontier research labs.
“We see this deal as risky,” Morningstar senior equity analyst Malik Ahmed Khan wrote, adding that since the company will be post-training open models, a widening gulf between the frontier and open models would put Palo Alto at a “slight disadvantage.”
Advertisement|Remove ads.
At the time of this writing, PANW stock was up over 9% in the premarket session, on track to extend the previous session’s nearly 10% gains.
AI Security Demand To Drive Growth
The note comes after Palo Alto reported first-quarter earnings on Wednesday, with sales up 39% year-over-year to $3.44 billion, beating the $3.31 billion consensus estimate tracked by Fiscal.ai.
Despite its concerns about the acquisition, Morningstar remains positive about Palo Alto's position in AI-related cybersecurity spending. It views the company as a cybersecurity leader, with platforms spanning network security, cloud security, identity, and security operations.
“We believe the firm stands to materially benefit from secular tailwinds across its three key end markets as cloud migrations, the shift to zero-trust security, and increased automation in cybersecurity increase Palo Alto’s value proposition to its clients,” the Morningstar note said.
Advertisement|Remove ads.
According to the analyst, Palo Alto’s sticky platforms, combined with the broad range of its cybersecurity solutions, have helped the company build a “wide economic moat around its business”.
PANW Valuation And Risks
Morningstar retained its $300 fair value estimate for PANW stock despite the company's strong quarterly performance, implying a potential downside of nearly 12% from the last closing price of $339.9 per share.
The research firm continues to favor Palo Alto's positioning in AI-related security spending and cybersecurity vendor consolidation. However, it assigned a “Very High” Uncertainty Rating, citing rapid technological change and potential disruption from smaller cybersecurity rivals.
Advertisement|Remove ads.
The firm warned that “an inaccurate assessment of future customer demand could lead Palo Alto to either overpay in an acquisition or overspend to develop the same technology in-house.” It also flagged talent shortages and data privacy and security as potential risks.
Meanwhile, Jefferies raised its price target on the stock to $450 from $400 and maintained a ‘Buy’ rating, citing another material acceleration in fiscal first-quarter core net new annual recurring revenue, driven by AI and observability tailwinds, according to TheFly.
The firm described the results as “another clean print,” with “AI tailwinds starting to emerge”. Jefferies’ target implies a potential upside of 32%.
What Retail Thinks About PANW Stock
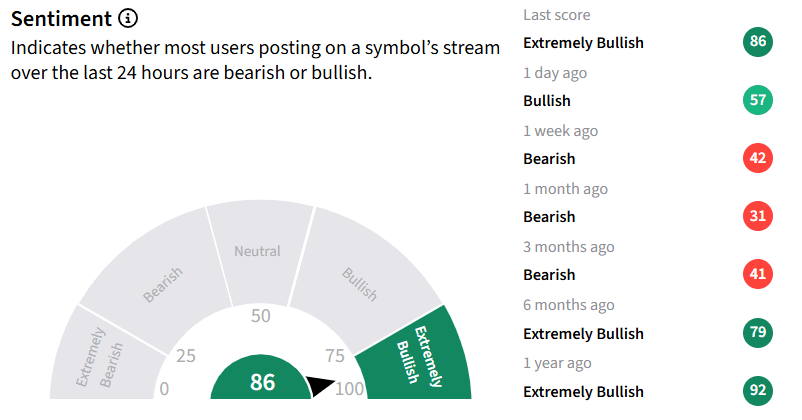
On Stocktwits, retail investors’ sentiment around PANW stock flipped to ‘extremely bullish’ from ‘bullish’ a day ago amid ‘extremely high’ user message volume. The stock was among the top-trending tickers on the platform.
Advertisement|Remove ads.
So far this year, PANW stock has surged over 89%. In comparison, the First Trust NASDAQ Cybersecurity ETF (CIBR) and the Global X Cybersecurity ETF (BUG), which hold Palo Alto shares, have risen over 35% and 56%, respectively, over the same period.
See Also: GTA VI Sales Top $1.6B — Take-Two, Console Partners Microsoft And Sony Shares Rise
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Advertisement|Remove ads.
Comments posted here will also appear on symbol pages.

Latest News
 Aveek Bhowmik·11m ago
 Arnab Paul·14m ago

 Harshita Tyagi·17m ago

 Shivani Kumaresan·1h ago
 Yuvraj Malik·2h ago
 Shivani Kumaresan·2h ago