


Advertisement|Remove ads.
PYPL Stock On Track To Reverse 3 Weeks Of Gains: Analyst Says Turnaround Story Will Take Time


- The revised target implies a downside of nearly 21% from the stock’s last close.
- Evercore noted that PayPal’s results were largely in line with expectations and its short-term outlook, adding that this reminded investors that while the company has potential, it will take time to unlock.
- The firm posted its third-quarter earnings on Tuesday, with revenue up 2% to $8.58 billion, missing analysts' estimates of $8.71 billion.
Advertisement|Remove ads.
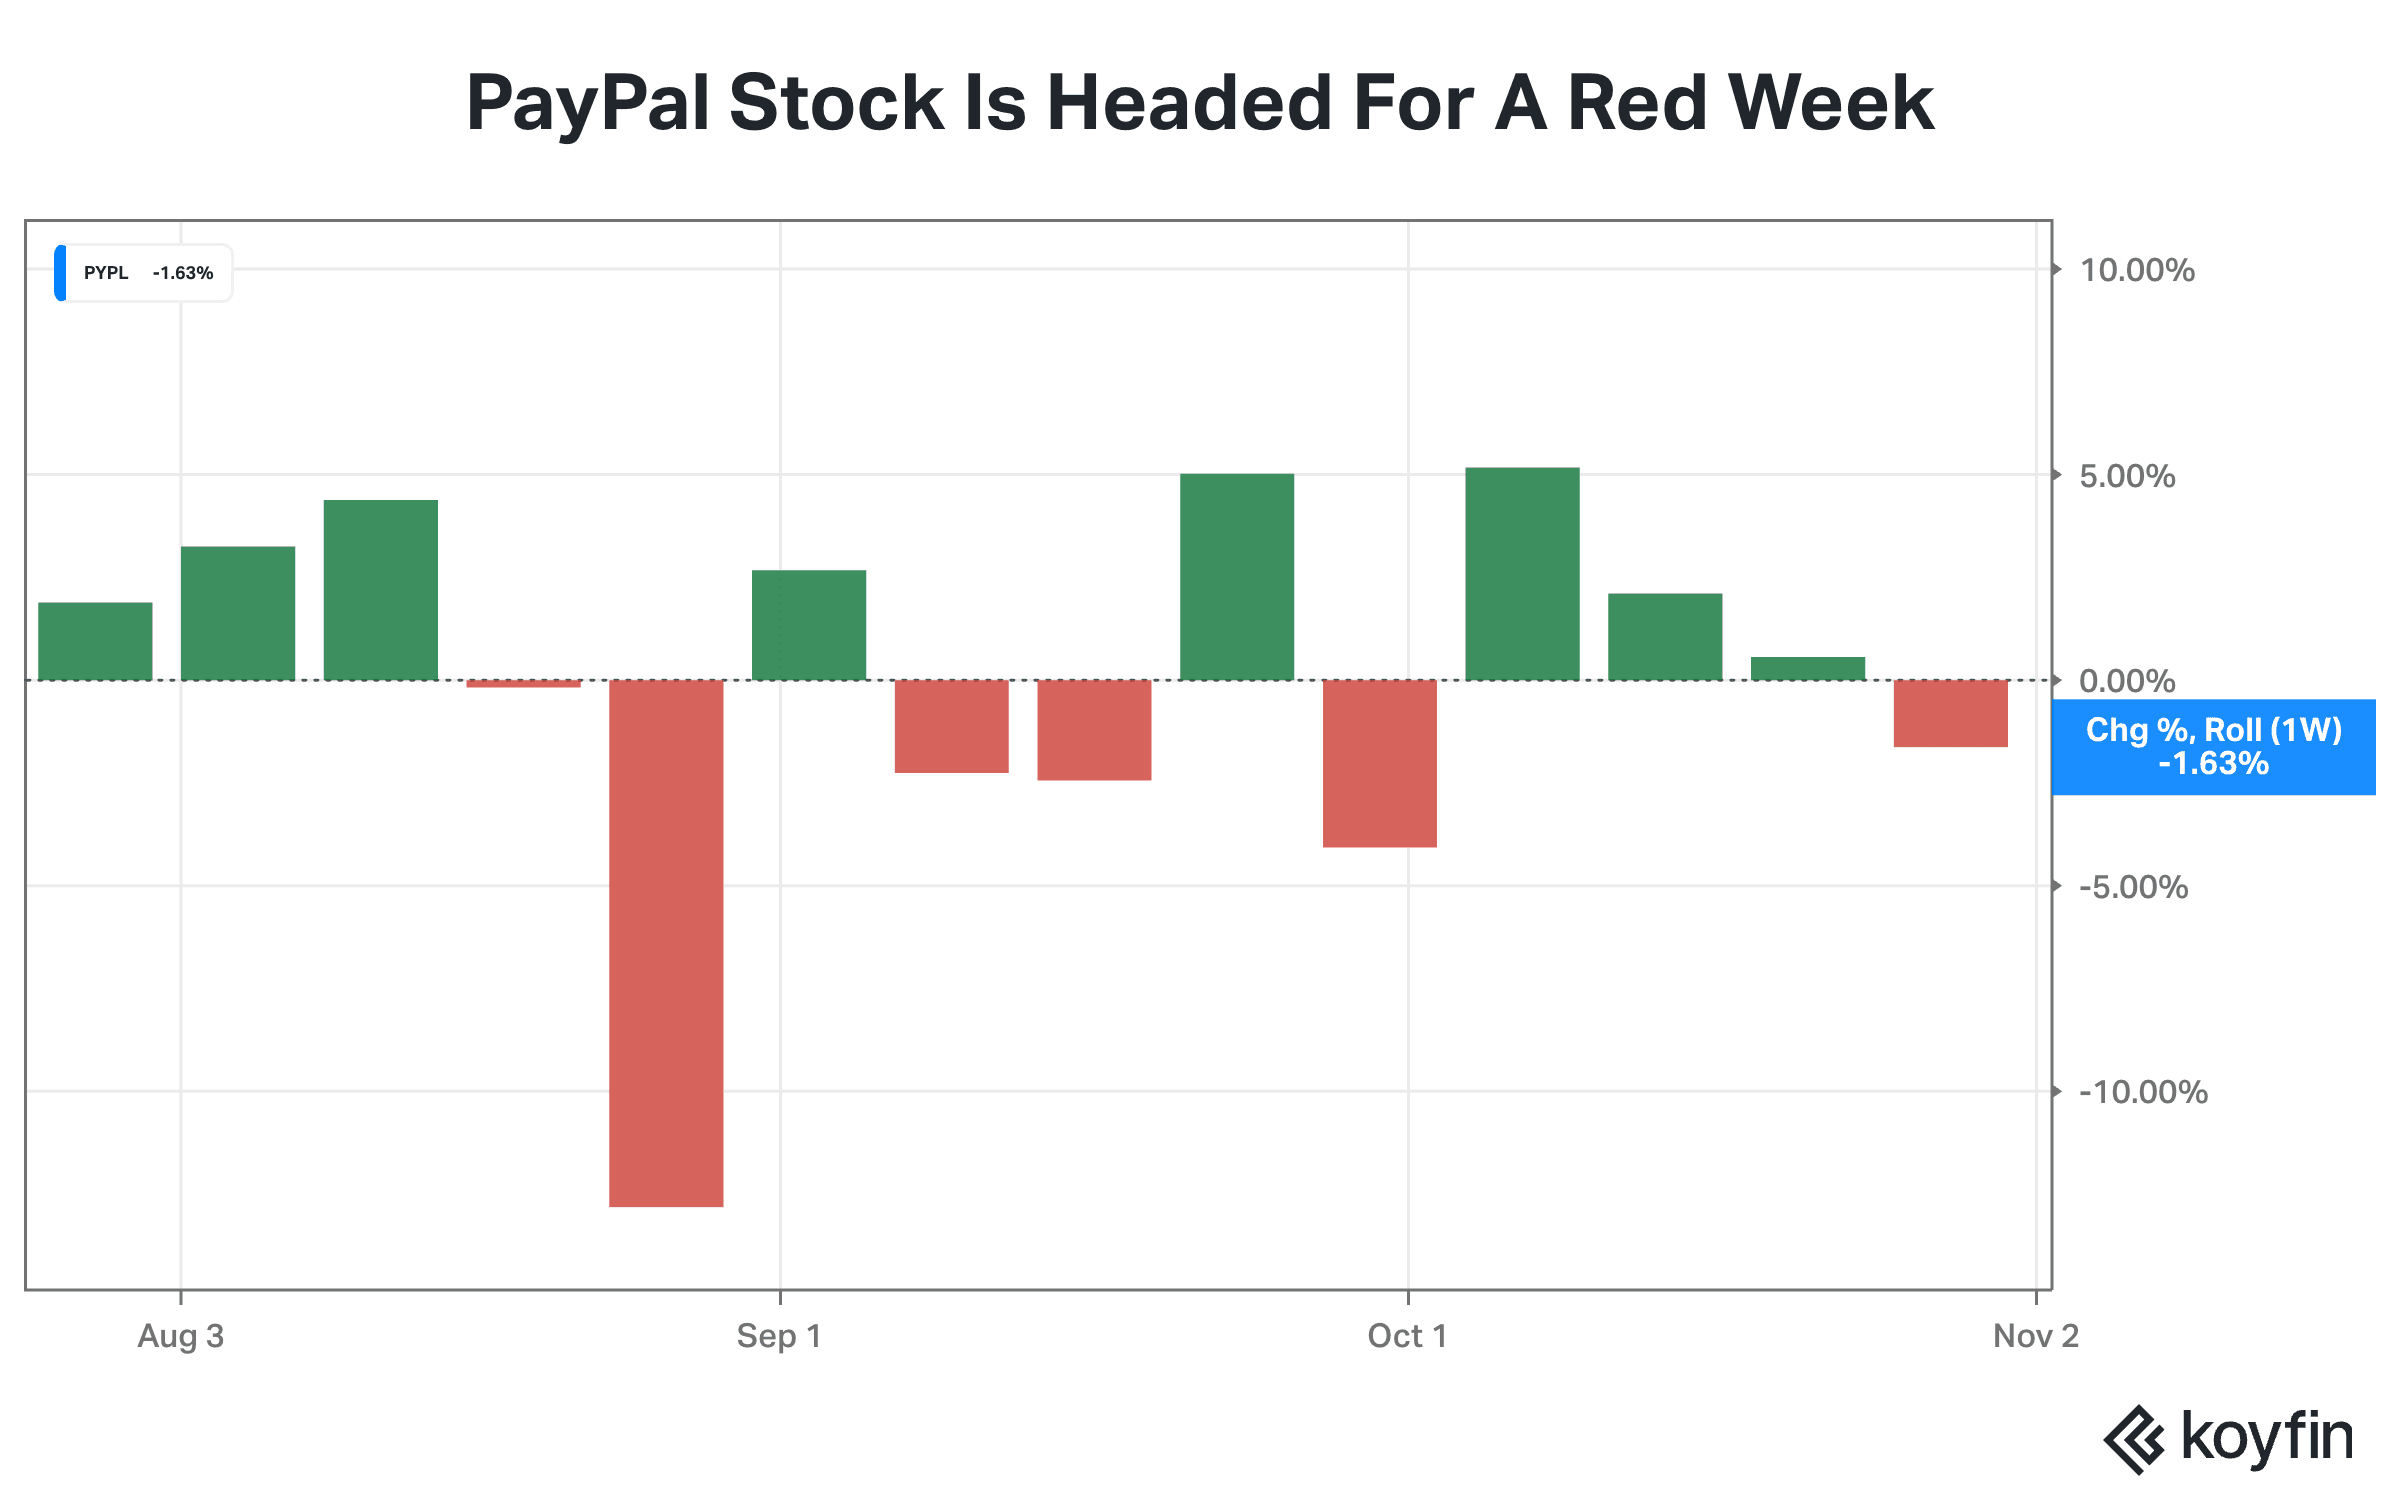
Shares of PayPal Holdings Inc. (PYPL) are headed for a week in red, on track to reverse three weeks of gains, shortly after posting its slowest quarterly net revenue growth of the year.
The firm posted its third-quarter earnings on Tuesday, with revenue rising just 2% to $8.58 billion, missing analysts' estimates of $8.71 billion, according to Koyfin.
However, Evercore ISI raised PayPal's price target to $45 from $40 and maintained an ‘In Line’ rating on the shares after the quarterly results. The revised target implies a downside of nearly 21% from the stock’s last close.
Advertisement|Remove ads.
Analyst Rationale On PYPL
Evercore noted that PayPal’s results were largely in line with expectations and the short-term outlook. The analyst said this reminded investors that while the company has potential, it will take time to unlock.
The firm said PayPal’s technology fix is still a multi-year process, and that growth will need to be funded through incentives and marketing spend, noting that expenses will likely fluctuate. These factors point to a longer-dated fundamental turnaround story, it said.
Evercore also noted that outside of mergers and acquisitions headlines and speculation, it finds it hard to see a scenario where shares can move materially and sustainably higher on the current fundamental trajectory.
Advertisement|Remove ads.
PYPL Stock: Retail Stance
On Stocktwits, retail sentiment around PYPL stock improved from ‘bullish’ to ‘extremely bullish’ over 24 hours.
One user said, “$PYPL Its a wonderful thing to behold. Paypal's ability to grow revenue come what may, with the consumer stretched as its ever been.”
Another user said, “$PYPL wow this is not even buybacks. It will climb even more when buybacks start back.”
Advertisement|Remove ads.
A third user said, “$PYPL solid company! I like this cash machine.”
PYPL stock is down about 3% in 2026.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Advertisement|Remove ads.
Comments posted here will also appear on symbol pages.
Latest News
 Shivani Kumaresan·18m ago
 Anushka Basu·18m ago
 Yuvraj Malik·39m ago
 Deepti Sri·1h ago
 Yuvraj Malik·2h ago
 Shivani Kumaresan·2h ago