


Advertisement|Remove ads.
CRWV Stock’s Weekly Sell-Off 'Overdone,' JPMorgan Says — Sees Robust AI Demand, Healthy Returns


- JPMorgan analyst Samik Chatterjee reiterated the ‘Overweight’ rating on CRWV stock.
- Cantor Fitzgerald analyst Brett Knoblauch said nearly all of CoreWeave’s planned 2027 capacity has already been sold.
- Nvidia CEO Jensen Huang said CoreWeave’s strength is improving and its cost of capital is declining.
Advertisement|Remove ads.
CoreWeave Inc. (CRWV)'s stock’s recent sell-off is overdone, according to JPMorgan, which remains bullish on the artificial intelligence (AI) cloud provider despite growing concerns about its borrowing costs.
CoreWeave shares plunged nearly 20% between Oct. 8 and Oct. 14, before rebounding nearly 6% on Thursday, as Nvidia (NVDA) CEO Jensen Huang sought to reassure investors about the company's financial health.
According to The Fly, JPMorgan analyst Samik Chatterjee said concerns over rising bond yields and whether AI revenue can support healthy returns for neocloud operators appear overdone relative to CoreWeave's fundamentals.
Advertisement|Remove ads.
The analyst said data-center demand “is robust and has improved in recent months, rather than moderated,” and maintained that CoreWeave's project-level economics remain sound, supporting healthy margins and cash-flow returns, per TheFly.
The firm reiterated its ‘Overweight’ rating on the stock. As of this writing, CRWV stock was down over 5% in the premarket session.
CRWV’s Debt Concerns
CoreWeave's recent sell-off pushed the stock to a 52-week low, while yields on its 2031 bonds climbed above 15%, reflecting concerns about the cost of financing its AI expansion. Fellow neocloud operators Nebius Group (NBIS) and IREN (IREN) also faced selling pressure.
Advertisement|Remove ads.
DA Davidson analyst Gil Luria issued a stark warning about CoreWeave's financial future, saying, “If the AI cycle sputters, or certainly if it doesn't turn over, CoreWeave is going to be the first to go. The equity value is going to be zero".
Speaking on the Prof G Markets podcast on Wednesday, Luria called CoreWeave a “poster child for bad behavior,” estimating that the company borrows at roughly 9% to finance investments that generate returns of just 1%.
He warned that even if those returns improved to 4% to 5%, they would remain below borrowing costs, raising questions about the sustainability of its debt-funded expansion.
Advertisement|Remove ads.
Nvidia's Huang Says CoreWeave Doesn't Need A Backstop
Nvidia CEO Jensen Huang defended CoreWeave's financial health on Thursday, telling Bloomberg that the company's strength was improving and its cost of capital was declining. He said CoreWeave did not need additional financial backing from Nvidia.
Nvidia (NVDA) holds approximately 10% of CoreWeave and has an agreement to purchase up to $6.3 billion of its unsold computing capacity through 2032. Huang's reassurances helped CoreWeave shares rebound on Thursday.
Cantor Fitzgerald Sees Buying Opportunity
Cantor Fitzgerald analyst Brett Knoblauch recommended buying the dip in CoreWeave, arguing that the spike in its bond yields to around 15% reflects concerns about funding massive artificial intelligence (AI) capital expenditures rather than weakening demand, according to The Fly.
Advertisement|Remove ads.
Knoblauch said nearly all of CoreWeave's planned 2027 capacity has already been sold, while Nvidia has an agreement to purchase residual unsold computing capacity.
The analyst also highlighted rising revenue per megawatt and improving contribution margins, which he said have shortened the payback period on chips to between two and 2.5 years.
Cantor believes improving unit economics and asset-backed financing can support CoreWeave's expansion and debt repayments. The firm maintained its ‘Overweight’ rating on CRWV stock with a target price of $176.
Advertisement|Remove ads.
What Retail Thinks About CRWV Stock
Despite the recent selloff in CoreWeave, Retail investors’ sentiment around CRWV stock flipped to ‘extremely bullish’ territory amid extremely high message volume.
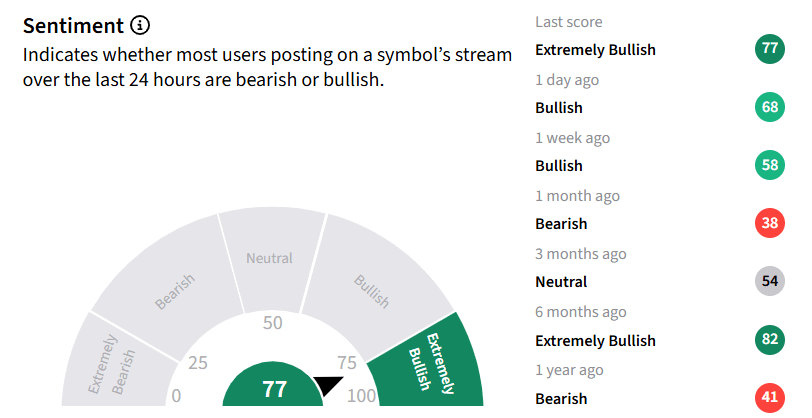
CoreWeave has erased all 2026 gains and is trading around 12% lower on a year-to-date basis. By comparison, the iShares Future AI & Tech ETF (ARTY), which holds the stock, has risen nearly 49% during this period.
Advertisement|Remove ads.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Comments posted here will also appear on symbol pages.

Latest News
 Shashank Nayar·7m ago

 Anan Ashraf·43m ago
 Prabhjote Gill·2h ago
 Anan Ashraf·2h ago
 Arnab Paul·2h ago
 Harshita Tyagi·2h ago