


Advertisement|Remove ads.
Micron CEO Says ‘We Cannot Fulfill The Demand’ As Supply Tightness Extends Through 2028

- More than 75% of Micron’s 2027 output is already committed, according to management’s comments on the earnings call.
- Mehrotra defended record employee incentive compensation, while pointing to an 86.35% gross-margin outlook.
- JPMorgan, Morgan Stanley and other firms emphasized the potential duration of the memory cycle, even as the pace of Micron’s quarterly earnings beats moderates.
Advertisement|Remove ads.
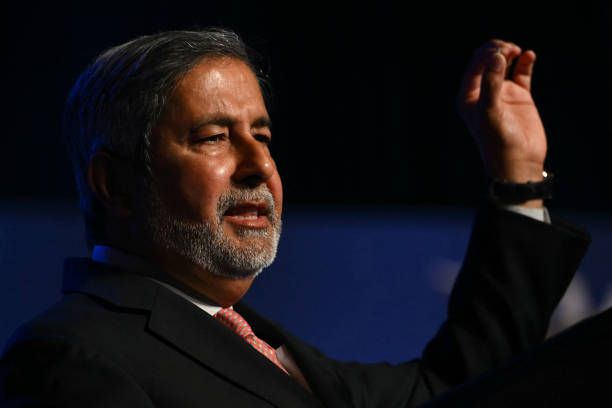
Micron Technology (MU) CEO Sanjay Mehrotra said on Thursday morning that demand for memory is outpacing the company’s ability to supply it, with tight market conditions expected to persist through 2028.
According to TheFly, analysts see that extended supply-demand imbalance supporting a longer period of strong pricing and earnings growth, even as the pace of Micron’s quarterly earnings beats begins to moderate.
“Not only do we have more customers and customers wanting to do long-term supply agreements with us,” Mehrotra said in an interview with CNBC after Micron’s fiscal fourth-quarter (Q4) results. “In fact, we cannot fulfill the demand of our customers.”
Advertisement|Remove ads.
MU stock dropped more than 2.5% in the morning trade and was the top-trending ticker on Stocktwits at the time of writing. On Stocktwits, retail sentiment around Micron trended in ‘extremely bullish’ territory at the time of writing.
Micron Sees Supply Tight Through 2028
Mehrotra said the company is seeing supply remain tight in both 2027 and 2028, while long-term customer commitments are extending well beyond the immediate cycle.
“We have extensions going into the 2031 time frame,” he said, adding that the agreements give Micron “tremendous visibility, certainty of demand” and confidence to plan manufacturing investments.
Advertisement|Remove ads.
Executives on the earnings call stated that Micron has more than 75% of its 2027 output already committed, with customer discussions increasingly focused on 2028.
Micron Defends Record Incentive Compensation
Mehrotra also addressed the impact of record incentive compensation on Micron’s costs following what he described as an “exceptional quarter.”
“To commensurate with our record quarter, we rewarded our team members in a record fashion as well,” he said, noting that the incentive compensation affected operating expenses in the fourth quarter.
Advertisement|Remove ads.
For manufacturing workers, some of that compensation is reflected in the first-quarter cost of goods sold and weighs on gross margin. Still, Mehrotra pointed to a “very strong” 86.35% gross-margin outlook.
“It is also important for us to attract, retain and motivate our talent so that our momentum continues,” he said.
Wall Street Sees Longer Earnings Runway
Mehrotra’s comments come alongside a series of bullish post-earnings calls from Wall Street.
Advertisement|Remove ads.
| Firm | Rating | Price Target |
| JPMorgan | Overweight | $1,540 |
| Morgan Stanley | Overweight | $1,200 |
| TD Cowen | Buy | $1,600 |
| RBC Capital | Outperform | $1,500 |
| DA Davidson | Buy | $2,100 |
| Mizuho | Outperform | $1,400 |
In a note to investors cited by TheFly, JPMorgan said the quarter as a “decisive beat-and-raise” and added that Micron’s improved outlook for supply-demand conditions, alongside a shift toward greater capital returns, supports a “strong multi-year earnings power narrative from here.” The firm also said it materially raised its estimates.
Micron’s Earnings Beat Moderates
Morgan Stanley’s Joseph Moore said the size of Micron’s earnings beats has moderated. After beating and guiding ahead of consensus on earnings per share by 20% to 40% over the previous three quarters, Micron beat by 5% and guided 6% above consensus this time.
That could represent “the new normal as Micron's visibility improves,” Moore said. He added that while sequential improvement has slowed, the “strength in the business continues to shine through” and the duration of the cycle is “still underappreciated by some.”
Advertisement|Remove ads.
Micron Has A ‘Strong Roadmap’ In AI Data Centers
TD Cowen highlighted revenue guidance that came in well above expectations and an earnings beat despite higher incentive compensation. The firm also pointed to improving demand durability, while noting that gross margins could approach a peak in mid-2027.
RBC Capital said tighter supply-demand conditions in 2027 and 2028 could reflect stronger demand and diminishing benefits from DRAM process migration. DA Davidson similarly argued that the prospect of tighter conditions in 2028 extends the potential runway for strong memory pricing and earnings growth.
Mizuho pointed to Micron’s “strong roadmap” in AI data centers and its extended demand visibility.
Advertisement|Remove ads.
MU stock has gained over 260% year-to-date and jumped almost 470% in the last 12 months.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Advertisement|Remove ads.
Comments posted here will also appear on symbol pages.

Latest News
 Prabhjote Gill·28m ago

 Heera Hari·33m ago
 Harshita Tyagi·34m ago
 Arnab Paul·35m ago
 Prabhjote Gill·42m ago
 Arnab Paul·2h ago