


Advertisement|Remove ads.
Stocktwits Weekly Spread: What Shaped Treasury Yields And The Dollar This Week

- The U.S. dollar index wrapped its fourth consecutive week of gains—its longest rally since early 2025.
- Benchmark 10-year Treasury yields slipped 4 basis points to 5.25% at week's end, while 30-year yields reached 5.60%.
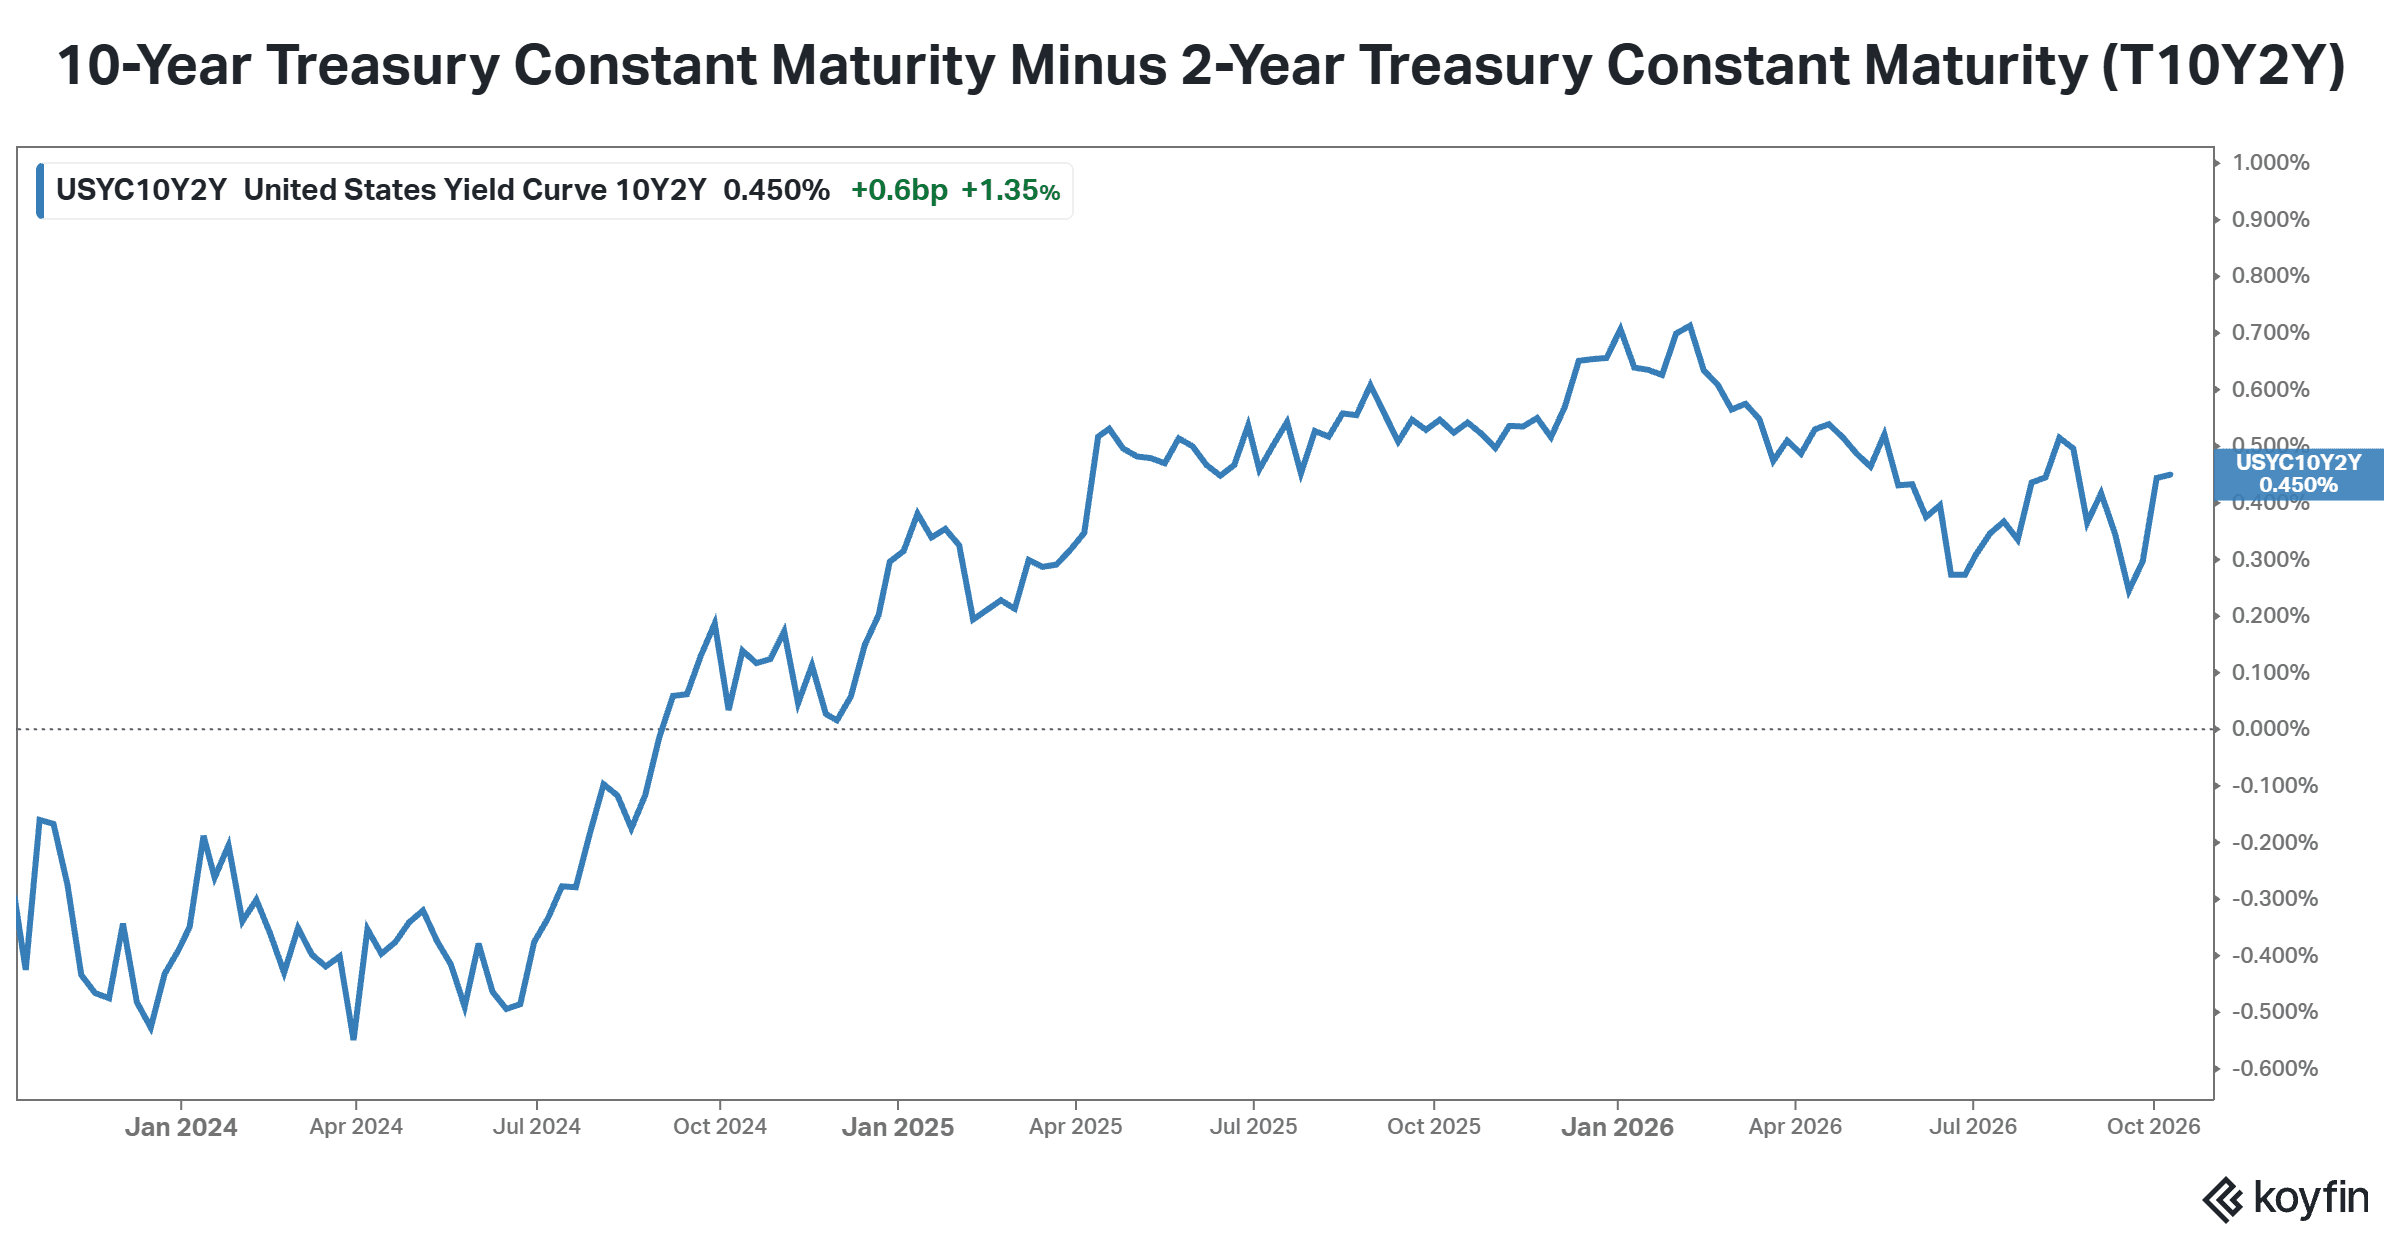
- The yield curve flattened further as 2-year yields rose 1 basis point to 0.45%, reflecting reduced market expectations for Federal Reserve rate cuts over the next 12 months.
Advertisement|Remove ads.
U.S. fixed-income and currency markets saw heightened volatility during the week ending Oct. 9, 2026, as a sustained surge in global crude oil prices reignited fears of persistent inflation.
Selling momentum returned to the U.S. Treasury market after a brief pause, keeping sovereign yields across short- and long-term tenors back around multi-decade peaks.
The relentless rise in yields continued to provide strong tailwinds for the U.S. dollar, which logged its seventh consecutive week of appreciation. Investors increasingly coalesced around the view that the Federal Reserve will be forced to maintain its restrictive policy stance well into next year as energy costs complicate central bank efforts to anchor consumer prices.
Advertisement|Remove ads.
"Energy markets are driving fixed-income sentiment right now... Higher oil prices act as a tax on consumers while simultaneously keeping the Fed on high alert against inflation," Kristina Campmani at Invesco told Bloomberg.
The 30-year U.S. Treasury yield hovered around 5.6%, while the 10-year yield eased slightly to 5.25% and 2-year yields settled at 4.80% for the week ending Oct. 9, similar levels to the previous week.
The spread between the U.S. 10-year yield and the U.S. 2-year yield ticked higher to 0.45% in the week, up from 0.44% a week ago.
Advertisement|Remove ads.
The iShares 20+ Year Treasury ETF (TLT) ended the week 0.7% higher, while the shorter-duration iShares 1-3 year ETF (SHY) added about 0.2%, recovering mildly after falling for six straight weeks. The slight recovery in the shorter-duration bond ETF may reflect easing short-term inflation pressure; however, markets still factor in one more rate hike in December.
Retail sentiment on TLT and SHY was ‘bullish,’ with ‘high’ message volumes.
| Asset / Benchmark | Weekly Close | Weekly Change |
| U.S. Dollar Index | 102.23 | +0.6% |
| U.S. 2-Year Treasury Yield | 4.80% | -3 bps |
| U.S. 10-Year Treasury Yield | 5.25% | -4 bps |
| U.S. 30-Year Treasury Yield | 5.60% | -1 bps |
| U.S. 10Y2Y Yield Spread | Flattening curve | - |
Yield Curve & Global Sovereign Markets
Yield curve flattening trends persisted as short-duration yields outpaced gains at the long end, keeping the gap between 2-year and 10-year Treasuries tightly compressed.
Advertisement|Remove ads.
The bond rout expanded across international sovereign bond markets. European government bond yields rose alongside U.S. peers, with German Bunds, UK Gilts and French bonds all gaining at the beginning of the week before tapering off slightly. However, they remain elevated amid soaring inflation pressures.
Greenback & Economic Data Roundup
The Bloomberg Dollar Spot Index gained 0.4% on the week to close at 1,212.40, marking its seventh straight weekly advance—the longest continuous rally for the U.S. currency since early 2025. Resilient domestic economic indicators and widening interest rate differentials relative to other major developed economies supported the dollar's strength.
Advertisement|Remove ads.
Next week’s U.S. inflation data is poised to provide critical guidance on the Federal Reserve’s monetary policy trajectory. While central bank officials executed their first rate increase since 2023 last month, money markets currently assign only a 20% probability to a follow-up adjustment in October, though market participants have already fully priced in a December rate hike.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Comments posted here will also appear on symbol pages.

Latest News
 Shashank Nayar·24m ago
 Shashank Nayar·31m ago
 Anan Ashraf·40m ago
 Shashank Nayar·2h ago
 Shashank Nayar·4h ago
 Anan Ashraf·4h ago