


Advertisement|Remove ads.
TSLA Stock Rises Overnight: Analyst Says SpaceX Merger Buzz Could ‘Dominate’ Near-Term Narrative — Gary Black Sees More Gains Ahead


- Baird maintained an ‘Outperform’ rating and $475 target, seeing potential SpaceX merger speculation dominating the near-term narrative.
- Tesla delivered 486,532 vehicles in Q3, beating expectations despite a 2% year-over-year decline.
- Analyst Gary Black estimated that a sustained delivery boost could add $0.15 to annual adjusted EPS and $32 per share to Tesla’s value.
Advertisement|Remove ads.
Shares of Tesla, Inc. (TSLA) rose 0.4% overnight heading into Tuesday as Baird said speculation about a potential SpaceX merger could dominate the near-term narrative, while analyst Gary Black saw further upside from Tesla’s third-quarter delivery beat.
TSLA stock jumped over 2% on Monday to $378.73, logging its second straight session of gains.
SpaceX Merger Speculation Takes Center Stage
Baird reiterated an ‘Outperform’ rating and $475 price target, implying 25% upside from current levels. “Recent investor focus has been on the Cybercab launch/robotaxi service scaling, and a potential merger with SPCX, the latter of which we expect will continue to dominate the narrative near term,” the firm said.
Advertisement|Remove ads.
Tesla reported 486,532 third-quarter deliveries, including 478,237 Model 3 and Model Y vehicles and 8,295 other vehicles. Production totaled 464,391, while energy-storage deployments reached 13.7 gigawatt-hours.
Deliveries fell about 2% from the year-earlier quarter, when the expiration of the U.S. $7,500 EV tax credit pulled purchases forward. Tesla reports earnings after the market closes on Oct. 21.
The research firm noted that Tesla’s delivery beat was largely driven by Model 3 and Model Y, while other models declined and missed consensus. Energy-storage deployments also missed expectations, although 10% annual growth kept the business a “bright spot on the P&L,” they said.
Advertisement|Remove ads.
Black Sees More Upside From Delivery Beat
Gary Black, managing director of The Future Fund, argued that Tesla’s stronger vehicle volumes could justify additional gains. Annualizing the 25,000-vehicle delivery beat, using 487,000 deliveries against a 462,000 estimate, he calculated a potential $0.15 increase in annual adjusted earnings per share if the improvement proves permanent.
The earnings boost “should be worth roughly $32/share to TSLA stock price,” he said on X. “TSLA is up +$23/share since Friday morning so there may be more near-term upside assuming the market is efficient,” Black added.
Wall Street Divides Over Tesla’s Next Act
Meanwhile, Truist maintained a ‘Hold’ rating and $370 target, implying a 2% downside from current levels. The firm said the delivery announcement offered no updates on AI projects or new vehicles, keeping its focus on FSD and the Optimus humanoid robot.
Advertisement|Remove ads.
“We view AI developments as far more important than auto deliveries for TSLA’s long-term cash generation and stock performance,” Truist said. It lowered its 2027 earnings estimate by $0.01 to $1.97 per share.
On the other hand, HSBC raised its target to $157 from $125 but retained a ‘Reduce’ rating. The revised target still implies 59% downside. The firm highlighted production running about 23,000 vehicles below deliveries, which could indicate expectations for a slower sales rate or reflect summer shutdowns. Energy deployments were 19% below Visible Alpha consensus and 24% below HSBC’s estimate, prompting a reduction in its full-year deployment forecast.
Morningstar had offered a more optimistic valuation, maintaining its $450 fair value estimate and calling Tesla “slightly undervalued.” Its estimate implies a 19% upside. Its earnings watchlist includes robotaxi expansion, Cybercab, FSD version 15 and Optimus.
Advertisement|Remove ads.
Musk Confirms TSMC Talks
Tesla’s semiconductor plans also drew attention over the weekend after Musk acknowledged discussions involving Taiwan Semiconductor Manufacturing (TSM) and Terafab, Tesla’s project with SpaceX. “Just discussions, but something may come of it,” Musk said, responding to a Culpium report about a potential agreement.
The report outlined possible arrangements involving factory ownership, equity contributions, purchase commitments or TSMC’s manufacturing expertise.
How Do Retail Traders Feel About TSLA?
On Stocktwits, retail sentiment for TSLA jumped to ‘bullish’ from ‘neutral’ levels a week ago amid a 374% jump in 24-hour message volumes.
Advertisement|Remove ads.
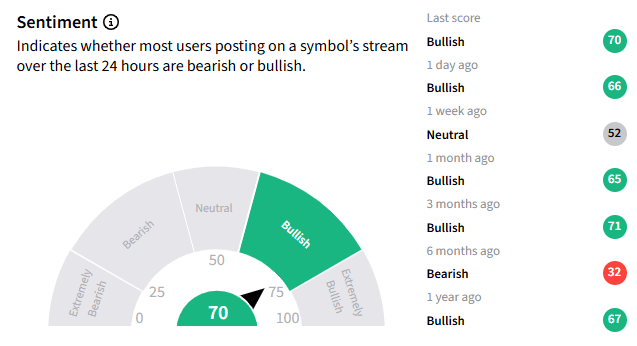
One user said, “$TSLA breakout tomorrow. Will run till 600 nonstop. All the analyst coming out of the mindset that Tesla is no more a car company. It's a AI and robotics company.”
Another user said, “$TSLA in October we will see Cybercab deployed in Dallas, and couple of other cities, robotaxi will start working in Las Vegas, number of Cybertrucks in Austin will continue growing. SP will exceed 400.”
Advertisement|Remove ads.
So far this year, Tesla's stock has lagged its "Magnificent Seven" peers, making it the group's worst performer, down about 16%.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Advertisement|Remove ads.
Comments posted here will also appear on symbol pages.

Latest News
 Deepti Sri·28m ago
 Aashika Suresh·29m ago
 Shivani Kumaresan·1h ago

 Yuvraj Malik·1h ago
 Deepti Sri·1h ago
 Deepti Sri·2h ago