


Advertisement|Remove ads.
AAPL Stock Downgraded As iPhone Shipment Concerns Mount — Analysts Flag Sales Growth Slowing

- UBS expects Apple's September quarter revenue to reach $112.8 billion, including $56 billion in iPhone sales.
- Loop Capital downgraded Apple to ‘Hold’, cutting its price target to $330 from $370 amid concerns about iPhone shipment plans and rising memory costs.
- Apple announced new and expanded U.S. manufacturing partnerships for its iPhone Duo and iPhone 18 Pro on Tuesday.
Advertisement|Remove ads.
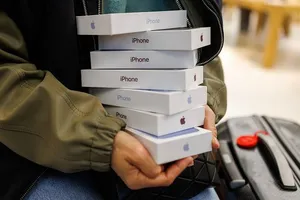
Wall Street is turning more cautious on Apple Inc. (AAPL) ahead of its November 2 earnings report as concerns around iPhone shipment trends and rising memory costs weigh on sentiment, offsetting enthusiasm around its first foldable iPhone Duo.
Loop Capital has raised concerns about whether shipment reductions can be recovered, while UBS has flagged slower revenue growth and margin pressure.
As of this writing, AAPL stock was trading more than 1% lower in the premarket session.
Advertisement|Remove ads.
Loop Downgrades AAPL
Loop Capital analyst Ananda Baruah downgraded Apple to ‘Hold’ from ‘Buy’ and lowered his price target to $330 from $370.
The firm initially believed Apple could recover many, if not most, of the units lost from a 10% reduction in planned iPhone shipments for the September and December quarters through 2027, assuming the cuts were driven by supply constraints rather than weaker demand.
“This no longer appears to be the case,” the brokerage said, signaling a shift in its assessment of the shipment reductions, per TheFly. The concern follows an earlier report that Apple had asked suppliers to cut October component orders for the iPhone 18 Pro models by at least 15%.
Advertisement|Remove ads.
Those component-order reductions are distinct from Loop's estimates for quarterly iPhone shipments. Loop also flagged potential gross margin risks from rising memory costs, arguing that Apple's stock “requires a fundamental catalyst reset” following its recent appreciation.
UBS Flags Margin Pressure
UBS maintained its ‘Neutral’ rating and $296 price target, citing margin pressures and Apple's valuation, which it said was at a five-year high.
UBS expects Apple to report September quarter revenue of $112.8 billion, including $56 billion in iPhone sales, broadly in line with expectations, and sees slowing iPhone growth and continued margin pressures.
Advertisement|Remove ads.
According to TheFly, the brokerage expects iPhone revenue growth to moderate to 14% year over year from 22% to 23% in recent quarters, as a 5% increase in average selling prices, driven by product mix and pricing, offsets a 5% decline in unit volumes.
iPhone Duo Demand Offers A Contrasting Signal
The cautious analyst commentary comes despite encouraging initial demand signals for Apple's first foldable smartphone, the iPhone Duo. Delivery estimates for the $1,999 device stretched into January 2027 shortly after preorders opened last Friday.
Evercore ISI viewed the extended delivery times positively but cautioned that they could reflect strong demand, constrained supply or both.
Advertisement|Remove ads.
Apple is scheduled to report its fiscal fourth-quarter earnings on November 2, when investors will get a clearer picture of iPhone sales, margins, and the impact of component costs.
Apple Expands US Manufacturing Partnerships
Apple announced new and expanded U.S. manufacturing partnerships for its iPhone Duo and iPhone 18 Pro on Tuesday. The company committed up to $100 million over three years to titanium supplier Perryman, which will produce material containing at least 80% recycled content for the foldable iPhone.
The iPhone maker is also expanding its partnership with Qnity Electronics (Q), which will produce advanced films for the iPhone 18 Pro's variable aperture camera system. The agreements are part of Apple's broader $600 billion, four-year commitment to U.S. manufacturing and innovation.
Advertisement|Remove ads.
Retail Investors’ Sentiment Around AAPL Stock
On Stocktwits, retail investors’ sentiment surrounding AAPL stock remained ‘extremely bearish’.
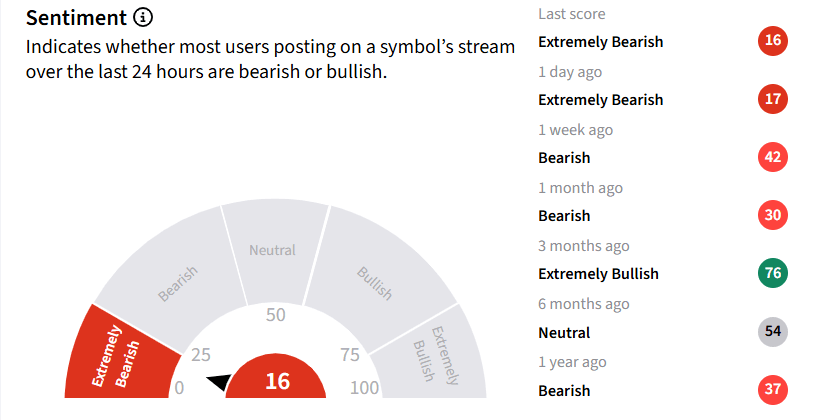
So far this year, AAPL shares have rallied over 26%, the best-performing stock among the Magnificent Seven. By comparison, the Invesco QQQ Trust, Series 1 (QQQ), and the Vanguard Information Technology ETF (VGT), which hold the stock, have risen around 17% and 27%, respectively, over the same period.
Advertisement|Remove ads.
For updates and corrections, email newsroom[at]stocktwits[dot]com
Comments posted here will also appear on symbol pages.
Latest News
 Anushka Basu·21m ago
 Harshita Tyagi·23m ago
 Prabhjote Gill·47m ago
 Harshita Tyagi·1h ago
 Prabhjote Gill·1h ago
 Heera Hari·1h ago