


Advertisement|Remove ads.
CAPR Stock Edges Higher Ahead Of Q3 Earnings, But Retail’s Attention Remains Firmly Fixed On Nov. 22 FDA Decision For Deramiocel


- Capricor ended June with $237.9 million in cash, equivalents and marketable securities, which is expected to fund operations for at least 12 months.
- HOPE-3 cardiac findings won an American Heart Association pediatric cardiology research award on Monday.
- Recently, 28 physician-scientists involved in HOPE-3 wrote to FDA leadership urging approval.
Advertisement|Remove ads.
Capricor Therapeutics (CAPR) was in the spotlight on Tuesday ahead of its third-quarter results, with investors closely watching for updates on the company’s operational runway ahead of a make-or-break regulatory decision on its genetic disorder drug on Nov. 22.
CAPR shares edged 1% higher in pre-market trading. The stock has seen sharp buying interest lately, closing in the red in just one session so far in November.
Q3 Net Loss Expected To Narrow
Analysts expect Capicor to post revenue of $10.4 million and a loss of $0.42 per share in Q3, according to Fiscal.ai data. While it posted a loss of $0.54 per share in the previous corresponding period, it did not record revenue.
Advertisement|Remove ads.
Sequentially, Capricor reported a $40.7 million loss, or $0.70 per share, in Q2, with no revenue.
Investors will look for updates on the company’s cash position. Capricor ended June with $237.9 million in cash, equivalents and marketable securities, which management said could fund operations for at least 12 months.
Retail Says PRV Could Significantly Extend CAPR’s Runway
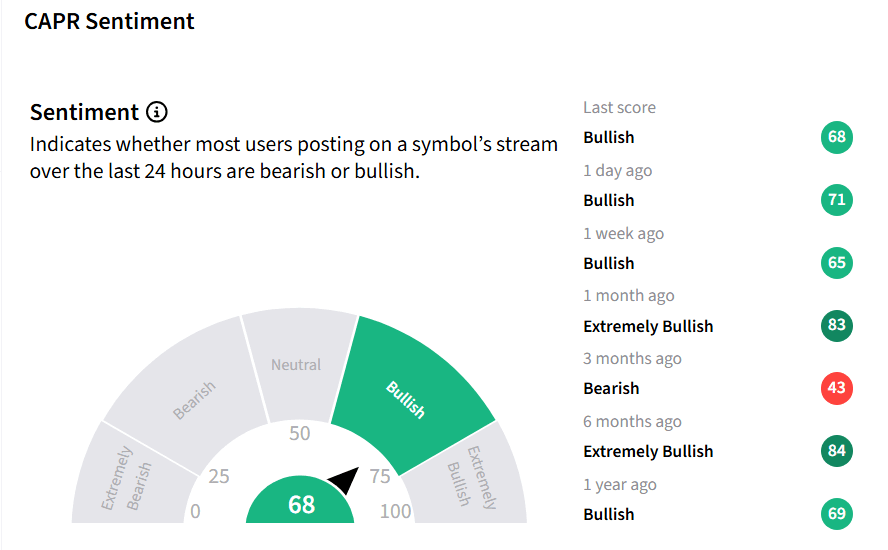
Retail sentiment surrounding CAPR on Stocktwits remained ‘bullish’ over the past 24 hours, amid a 492% surge in message volumes. CAPR was also among the top trending tickers on the platform at the time of writing.
Advertisement|Remove ads.
Retail investors remained focused on the U.S. Food and Drug Administration’s (FDA) Nov. 22 decision on Deramiocel, its experimental treatment for Duchenne muscular dystrophy (DMD), a genetic disease that causes progressive muscle weakness.
One user said that while they do not expect much substance about Deramiocel in the earnings call, they are ‘strongly bullish’ on FDA approval. “A squeeze to $50+ is still very much on the table if we get approval.” The stock is trading close to $10.
Advertisement|Remove ads.
Another user is hopeful for a Priority Review Voucher (PRV) from the FDA, which could sell for about $200 million and significantly extend the company’s cash runway. A PRV allows a drugmaker to seek a faster FDA review of another drug application, or sell the voucher to another drugmaker.
Advertisement|Remove ads.
FDA Decision Takes Center Stage
The FDA pushed its verdict date from August to Nov. 22 after Capricor submitted additional HOPE-3 trial data supporting a revised application focused on preserving arm and hand function. An advisory panel had voted 9–3 against evidence supporting the drug for DMD-related heart disease in July.
However, Capricor said on Monday, HOPE-3 cardiac findings won an American Heart Association pediatric cardiology research award. Recently, 28 physician-scientists involved in HOPE-3 wrote to FDA leadership urging approval, citing the lack of effective approved options for non-ambulatory DMD patients.
Oppenheimer Sees Approval Potential
Last month, Oppenheimer reiterated an ‘Outperform’ rating and $54 target, arguing that additional analyses of upper-limb benefits supported a greater likelihood of approval than CAPR’s share price suggested.
Advertisement|Remove ads.
The stock had crashed more than 60% between June 30 and Sept. 30, after the advisory committee vote.
The stock has a 12-month price target of $27, according to Koyfin. Of the 10 brokerages covering the stock, four have a ‘Buy’ rating, while six have ‘Hold.’
CAPR shares have slumped more than 65% so far in 2026.
Advertisement|Remove ads.
For updates and corrections, email newsroom[at]stocktwits[dot]com.
Comments posted here will also appear on symbol pages.

Latest News

 Arnab Paul·9m ago

 Prabhjote Gill·30m ago

 Harshita Tyagi·43m ago
 Aveek Bhowmik·1h ago
 Shivani Kumaresan·3h ago

 Yuvraj Malik·3h ago